The Fed Cut Rates Yesterday – Hear’s What you Need to Know
Table of Contents
Yesterday the Federal Reserve cut the federal funds rate – the interest rate on overnight loans between banks, which the fed effectively controls – by a quarter point. There are four things you should know about that cut:
* although donald Trump has been screaming at the Fed, demanding big rate cuts, there isn’t actually a compelling case for cuts right now.
* On the other hand, this cut is unlikely to do any harm.
* actually, Fed policy over the next few months barely matters.
* The vital questions now are political: Will Trump destroy the Fed’s independence, and do to monetary policy what he has done to health policy – put it in the hands of charlatans and cranks?
Why do I say that there isn’t a compelling case for a rate cut? The Fed has a “dual mandate”: It’s supposed to seek both price stability and full employment. To fulfil this mandate as best it can, the Fed normally cuts interest rates when the job market is…
Image of Federal Reserve building – Source: CNBC survey
The Fed is About to Make a Huge Mistake
For over a year, the Federal Reserve has been aggressively raising interest rates in an attempt to combat inflation. While inflation has indeed come down from its peak,the Fed seems resolute to continue tightening monetary policy,even in the face of growing evidence that their actions are causing meaningful damage to the economy. I believe this is a huge mistake,and one that will have serious consequences for all Americans.
The core problem is that the Fed is operating with a flawed understanding of the current economic situation. They are fixated on lagging indicators – data that reflects past economic activity – rather than focusing on forward-looking signals. For example, they continue to point to a strong labor market as justification for further rate hikes. Though,the labor market is already showing signs of cooling,with job openings declining and unemployment claims rising.
Furthermore, the Fed is ignoring the impact of supply-side factors on inflation. Much of the initial surge in inflation was caused by disruptions to global supply chains, exacerbated by the war in Ukraine.These supply-side issues are gradually resolving themselves, and further rate hikes will do little to address them.Instead, they will simply increase borrowing costs for businesses and consumers, leading to a slowdown in economic growth.
The risk of a recession is now very high.The yield curve – the difference between long-term and short-term interest rates – is deeply inverted, a reliable predictor of recessions. Bank lending standards are also tightening, making it harder for businesses to access credit.
The Fed needs to change course.They should pause their rate hikes and begin to assess the full impact of their previous actions. They should also focus on monitoring forward-looking indicators and be prepared to reverse course if the economy weakens further.
Continuing down the current path will only lead to a painful recession and unnecessary hardship for millions of Americans. the Fed has a obligation to protect the economy, and right now, they are failing to do so.
The Fed, R-Star, and the Shifting Economic Landscape
What’s that about? Because the Fed tries to fulfil its dual mandate, it normally tries to set interest rates neither too high, which can lead to unnecessary unemployment, nor too low, which can lead to excessive inflation. If you ask me, the Fed should call its target the “Goldilocks rate.” Sadly, however, it’s usually referred to, unpoetically, as r* or r-star.
R-star can’t be observed directly, only estimated. And what has happened since last year is that many estimates of r-star have been marked up, for at least two reasons. first, the tax cuts in the One big Beautiful Bill will lead to larger budget deficits – no, tariff revenues won’t make up the difference, even if the Supreme Court lets Trump’s clearly illegal tariffs stand. And these deficits will put upward pressure on long-term rates. Second, the
Concerns Mount Over Potential Political Interference at the Federal Reserve
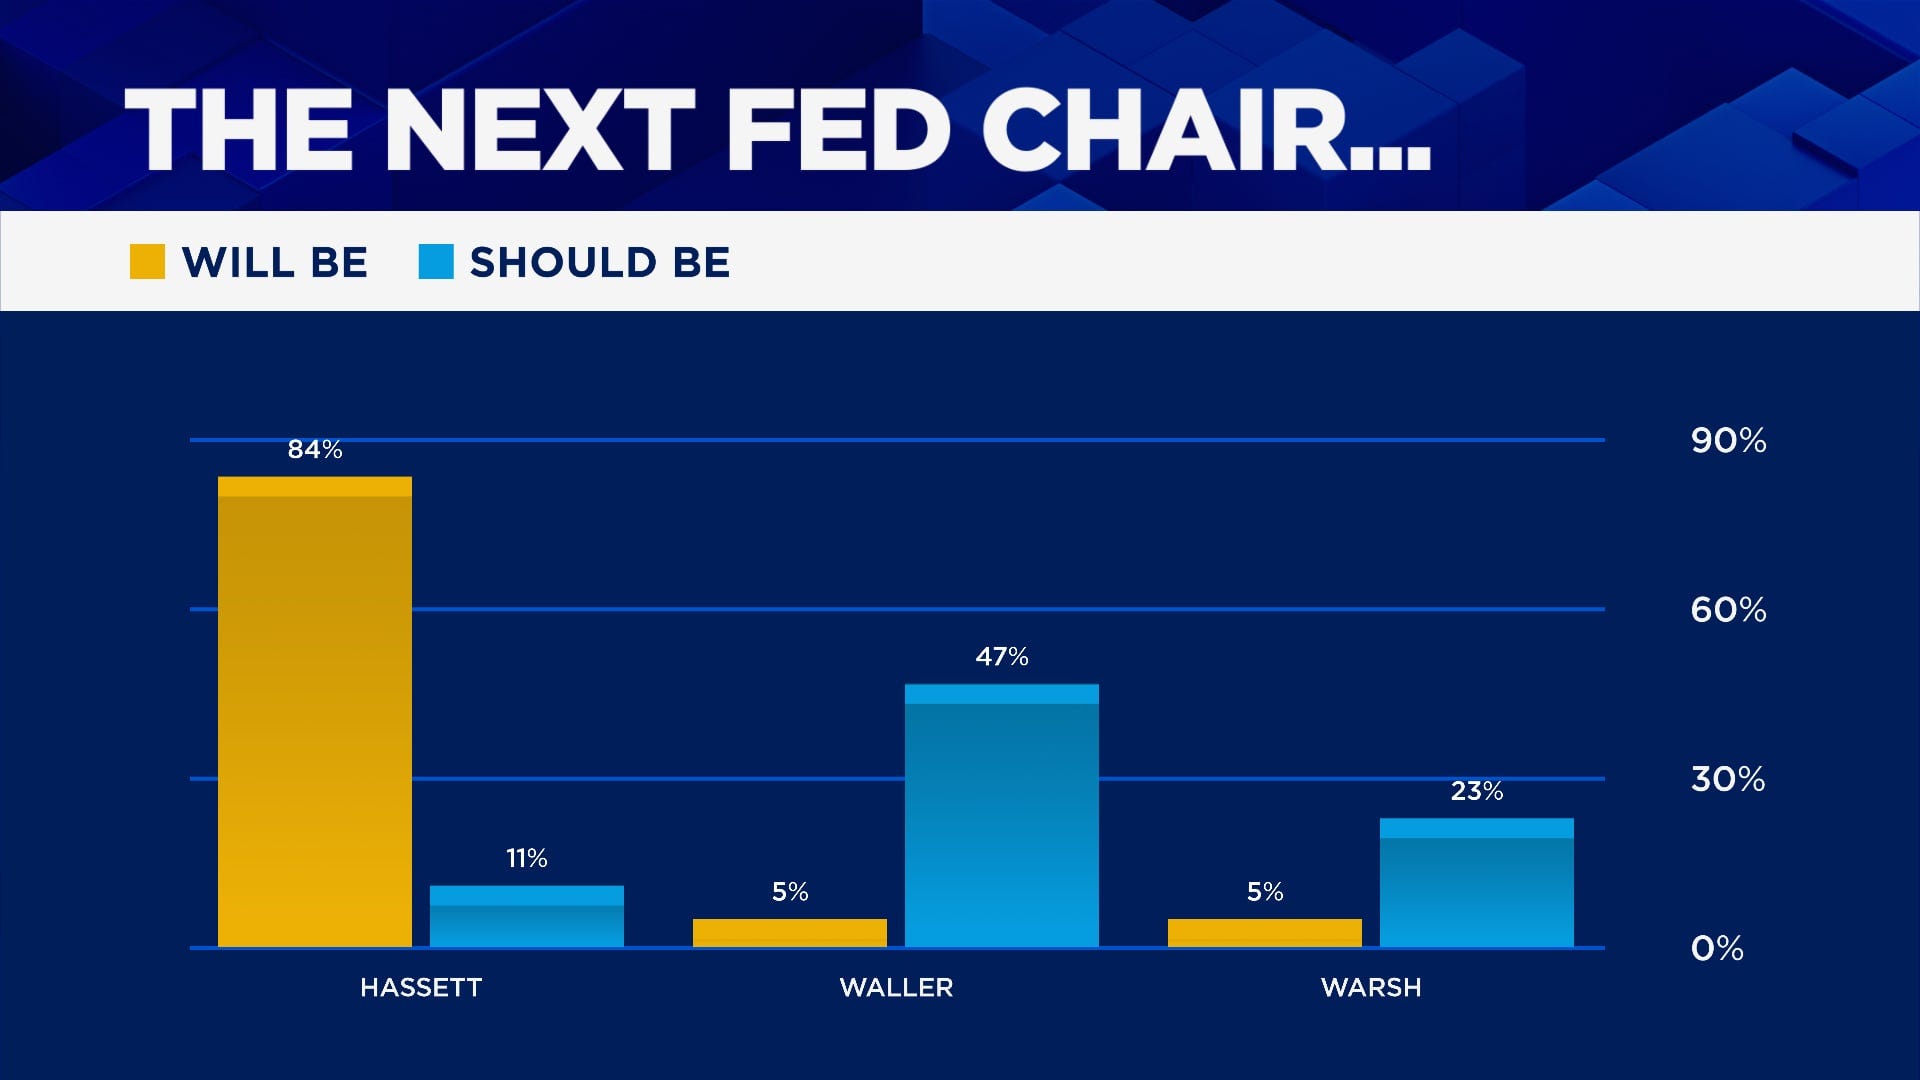
Paul Krugman expresses significant concern over the potential for political interference in the Federal Reserve, notably regarding the next chair nomination. A recent CNBC Fed survey indicates that while Kevin Hassett is widely expected to be nominated by Donald Trump, the vast majority of experts believe he is not the right choice.
Krugman argues that nonetheless of who is ultimately selected, the appointment is highly likely to result in a Fed chair overly deferential to Trump, which would be detrimental to the economy. He points to Trump’s contradictory demands for substantial interest rate cuts despite claiming the economy is in excellent condition as evidence of a perhaps hazardous and incoherent policy direction. Furthermore, Trump’s repeated, and demonstrably false, claims of falling prices raise concerns about his understanding of inflationary pressures.
Even if Trump doesn’t achieve complete control over monetary policy, Krugman warns that a politically aligned Fed chair would lack the necessary leadership, gravitas, and credibility to effectively navigate future economic crises. He highlights the challenging economic landscape currently facing the Fed, including persistent, though moderating, inflation, a softening job market, substantial future deficits, and a declining dollar (as indicated by the falling U.S. dollar Index [https://fred.stlouisfed.org/graph/fredgraph.png?g=1OIjw&height=490]). Krugman emphasizes that the credibility the Fed demonstrated during the 2008 financial crisis and the COVID-19 pandemic would be jeopardized by installing a “Trump sycophant” in the chair position.
Ultimately, Krugman concludes that political considerations are now paramount for the future of the Federal Reserve, overshadowing even specific policy debates like the timing of potential rate cuts in 2026.
Krugman will be hosting a live substack discussion with Heather Cox Richardson today at 11:00 AM [https://heathercoxrichardson.substack.com/].
Worth a look