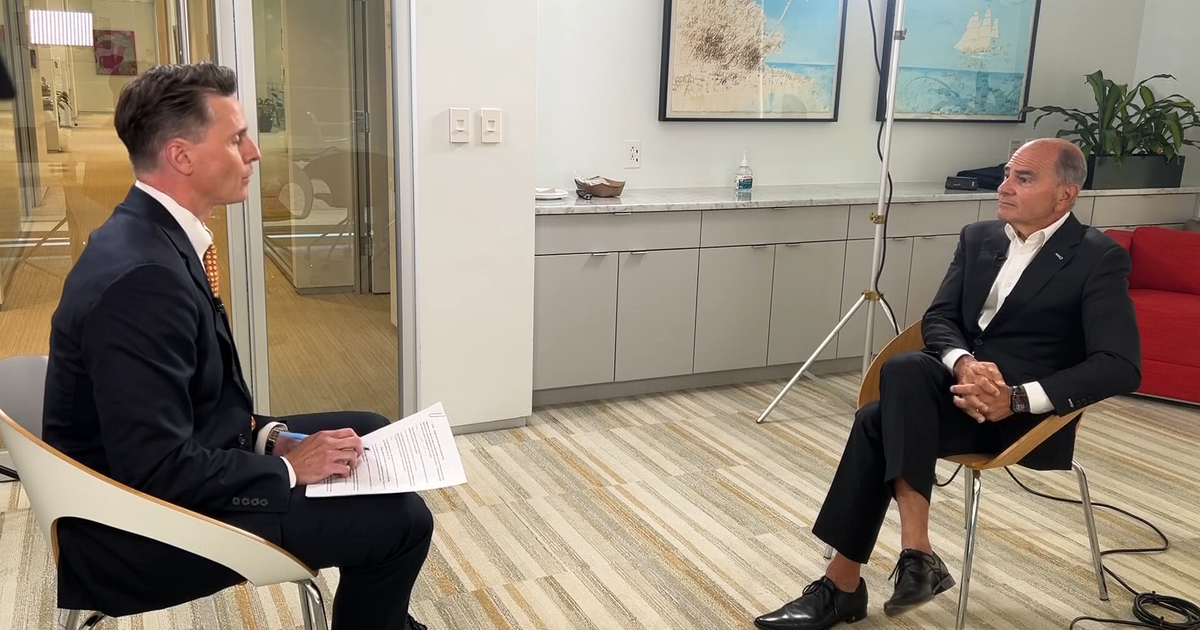
WakeMed CEO Donald Gintzig addresses potential cost impacts for patients as health systems evaluate consolidation, noting that market dynamics and regulatory oversight remain central to pricing discussions. Healthcare integration strategies across North Carolina continue to draw scrutiny from consumer advocates and healthcare economists regarding potential shifts in out-of-pocket expenses.
Health System Consolidation and Patient Pricing
As large healthcare networks explore partnerships and mergers, hospital executives face persistent questions regarding how consolidated operations affect patient billing. According to discussions surrounding system alignments like potential discussions involving Atrium Health and regional providers, proponents argue that scale improves operational efficiency and expands specialized care access. Critics and consumer watchdogs, however, contend that reduced market competition can grant health systems greater leverage in commercial insurance negotiations, frequently leading to higher premiums and facility fees for patients.
Economic analyses published by health policy researchers consistently indicate that hospital consolidation often precedes price increases in outpatient and inpatient services. When a single health system dominates a regional market, local employers and commercial insurers possess fewer alternative networks to negotiate against, resulting in higher contracted rates that eventually trickle down to patients through increased deductibles and copayments.
Regulatory Oversight and Antitrust Scrutiny
State and federal regulatory bodies maintain strict oversight frameworks to evaluate whether proposed healthcare mergers violate antitrust laws or substantially lessen market competition. The Federal Trade Commission (FTC) and state attorneys general review financial disclosures, patient migration patterns, and service overlap to determine consumer impact.
- Antitrust Reviews: Regulators assess whether combined market share creates pricing monopolies.
- Community Benefit Commitments: Health systems often pledge to maintain charity care and service lines as a condition of approval.
- Quality Metrics: Systems must demonstrate that integration improves clinical outcomes rather than merely driving revenue growth.
Financial transparency remains a primary tool for consumer protection. State healthcare cost commissions track average prices for common procedures across different facilities, allowing patients to compare costs before scheduling non-emergent care.
Evaluating Financial Impact for Consumers
For patients navigating large health networks, understanding how billing structures change post-consolidation requires examining facility fee policies and insurance tiering. When independent physician practices become hospital-affiliated clinics, patients frequently encounter two separate charges on a single medical bill: a professional fee for the physician’s service and a facility fee for the overhead of the building.
| Provider Model | Billing Structure | Typical Cost Impact |
|---|---|---|
| Independent Practice | Single professional fee | Generally lower out-of-pocket expenses |
| Hospital-Affiliated Clinic | Professional fee plus facility fee | Higher overall charges and cost-sharing |
Consumers can mitigate unexpected medical expenses by verifying network participation directly with their insurance provider and requesting detailed estimates before undergoing scheduled procedures at newly consolidated facilities.