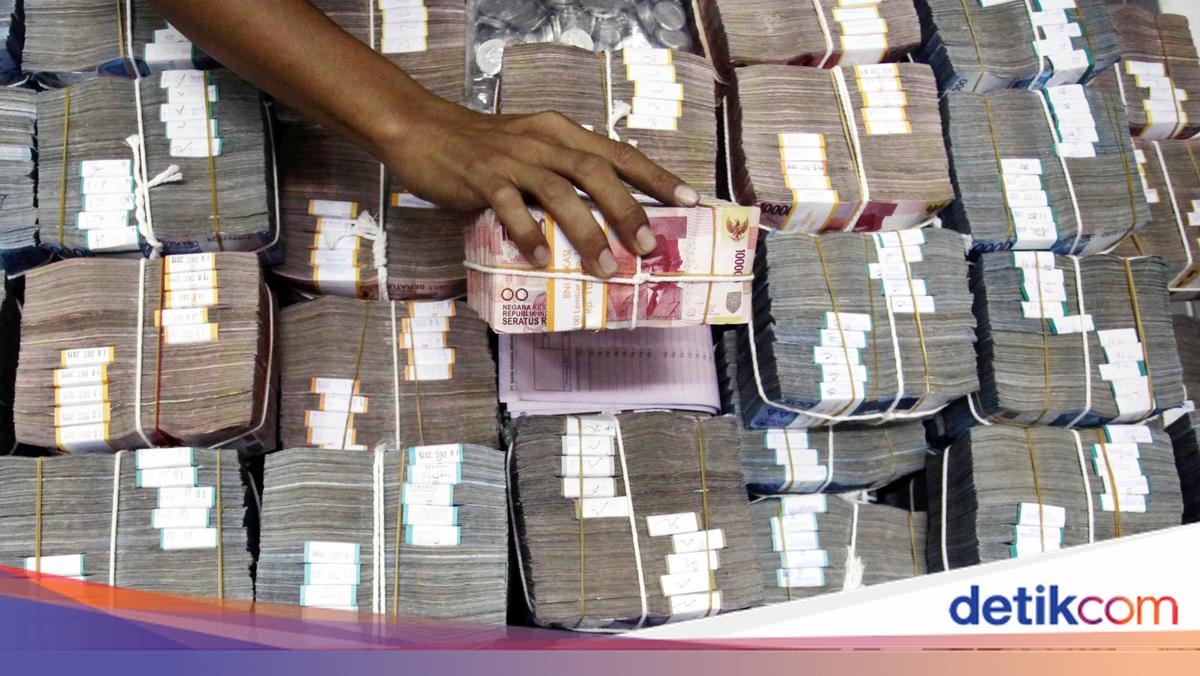
Undisbursed loans in Indonesia reached approximately Rp 2.548 triliun by July 2026, driven by a combination of sluggish private sector demand and banks prioritizing liquid government securities.
Demand-Side Pressures and Government-Led Growth
Credit growth through the second quarter of 2026 relied heavily on government-led initiatives rather than strong corporate expansion. Destry Damayanti explained that private sector demand has yet to gain full momentum, keeping the pool of undisbursed credit facilities elevated at roughly Rp 2.500-an triliun. Despite this broader corporate hesitation, Bank Indonesia has detected early indicators of shifting demand from private enterprises, signaling a gradual uptick in commercial economic activity.

“Why is the undisbursed loan still at the Rp 2.500-an triliun level? From the demand side, if we look at this credit growth up to the second quarter, it is still largely driven by the government-led sector,” Destry said during a press conference at Bank Indonesia offices in Central Jakarta on Thursday, September 24, 2026.
Banking Sector Liquidity and Monetary Incentives
On the supply side, financial institutions previously elected to park excess liquidity in risk-free government and central bank paper rather than extending corporate loans. Banks favored instruments such as Government Securities (SBN) and Bank Indonesia Rupiah Securities (SRBI) over traditional lending channels.
To counteract this trend, Bank Indonesia deployed a system of incentives and disincentives utilizing the statutory reserve requirement, known as Giro Wajib Minimum (GWM). Institutions that allocate excessive liquid assets to securities rather than loans receive no reserve requirement relief. Conversely, banks maintaining lower holdings of government paper while actively channeling funds into loans secure reductions in their GWM obligations, freeing up additional capital for lending.
“We look at which banks are disbursing credit even though they have liquidity. So we know that Himbara is currently the most active, but we also see several banks where demand has started to emerge,” Destry noted, referencing Indonesia’s state-owned bank cluster.
Productive Sector Expansion in August 2026
Lending metrics showed tangible improvement entering the final months of the third quarter. Bank Indonesia reported that total credit growth reached 13,6% in August 2026, paced by increases in investment loans and working capital financing directed toward productive economic sectors.
“Actually, this is a good thing because it means credit growth is entering the productive sector. So this is a signal for us that economic activity continues to turn with its economic capacity increasing because of the investment credit mentioned earlier,” Destry concluded.
Related reading