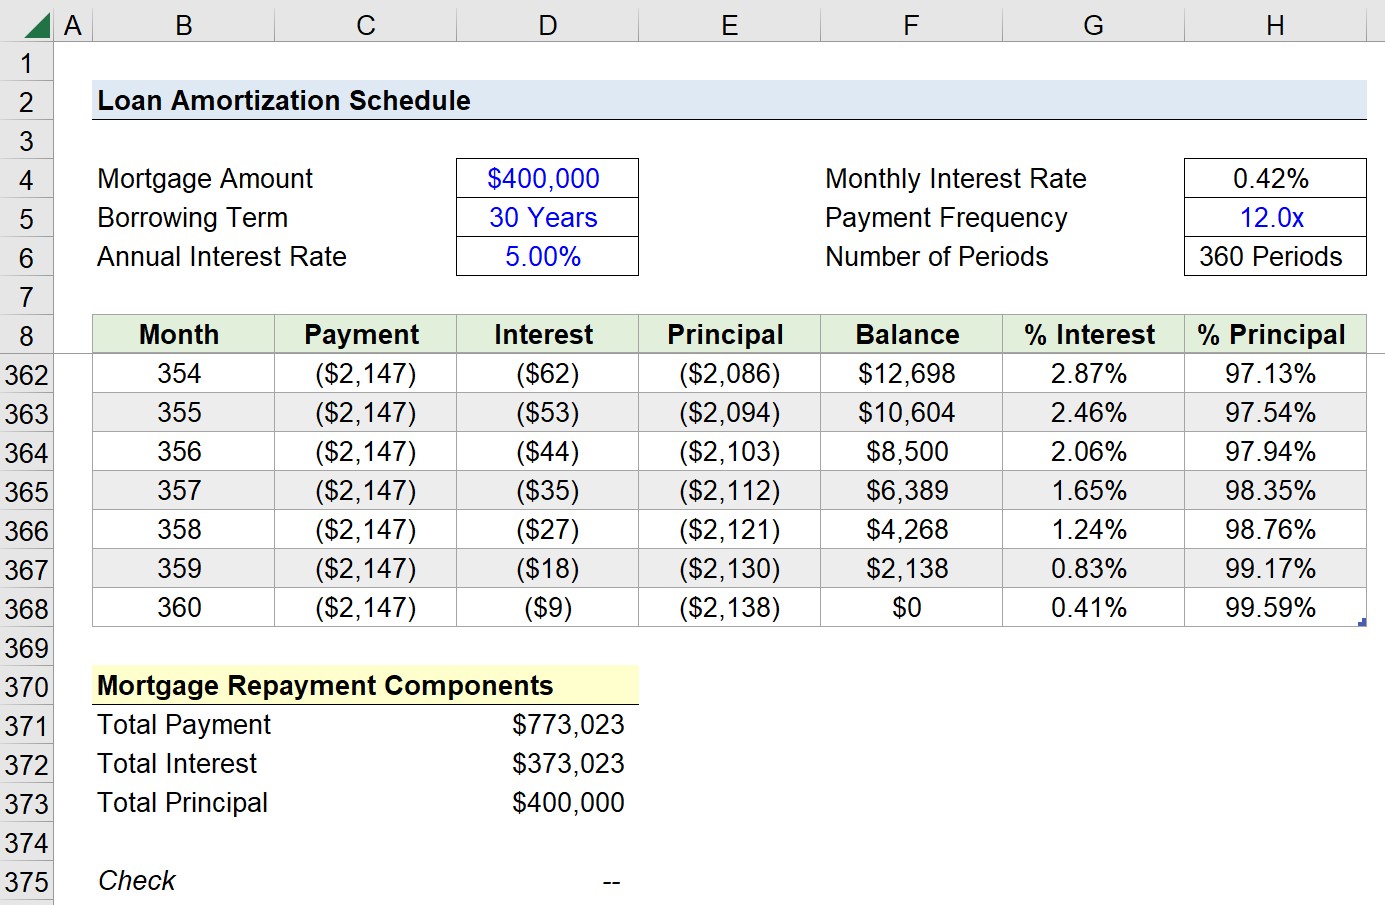
Real estate investors analyzing debt strategies face a choice between rapid loan amortization and maintaining lower monthly payments to preserve liquidity for portfolio expansion. Opting for a minimal principal repayment rate, such as 1 percent instead of 3 percent, keeps the remaining debt higher for a longer period, which increases total interest costs over the life of the loan.
The Amortization Dilemma in Real Estate Debt
Understanding Tax Deductions and the Cost of Capital
For rental properties, ongoing interest payments qualify as deductible business expenses, known in Germany as Werbungskosten. According to standard real estate financing principles, a higher interest burden generates a larger tax advantage, whereas faster amortization reduces total interest and simultaneously diminishes that tax shield.
The Opportunity Costs of Full Leverage Elimination
Completely paying off a property without borrowing introduces opportunity costs. Capital trapped in a fully owned asset generates no portfolio growth or scaling benefits, as equity remains locked in a single location rather than working across multiple units.
Preserving Cash Flow for Portfolio Debt
Maintaining a lower repayment rate ensures that monthly debt service remains manageable. Banks evaluate a borrower’s household budget and monthly financial obligations closely when reviewing applications for subsequent loans. Borrowers who amortize too quickly reduce their available cash flow and weaken their paper liquidity profile, making it more difficult to finance a second or third property.
Scaling Across Multiple Properties
Utilizing a lower monthly rate leaves capital free to acquire additional assets. This strategy allows investors to use borrowed funds across a portfolio of multiple properties simultaneously, letting concurrent market appreciation work on a larger asset base rather than a single paid-off holding.
Worth a look