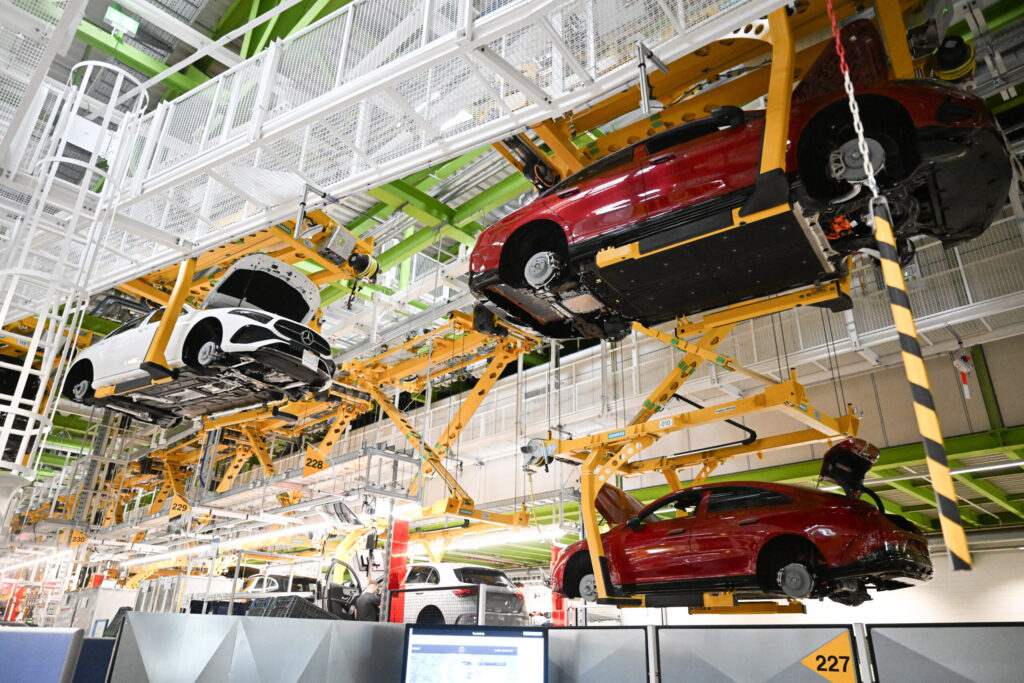
Central and Eastern Europe faces mounting economic strain as slowing demand and structural pressures in Germany threaten to undermine the region’s vast manufacturing base. According to a September 2026 analysis published by the Atlantic Council’s GeoEconomics Center by Charles Lichfield, industry accounts for between 21 and 33 percent of national gross domestic product across Central and Eastern Europe, positioning the area as a vital internal production platform for European reshoring strategies.
Industrial Exposure in Czechia and Slovakia
Czechia and Slovakia remain acutely vulnerable to economic shifts in Germany due to deep supply chain integration. Czechia sends 32 percent of its exports directly to Germany, with a sixth of its exporters relying exclusively on the German market. Slovakia exhibits even higher exposure, as total exports approach 90 percent of its GDP, and automobiles account for 34 percent of those outgoing shipments. As Europe’s automotive sector faces mounting pressure, these high concentration levels leave both countries exposed to potential contractions.
Germany’s economic malaise has intensified as imports of cars, capital goods, and industrial machinery from China rise rapidly while Chinese demand for European exports declines. This dynamic has generated job cuts across German manufacturing and fueled growing calls for protective trade measures. Because foreign direct investment stock in Central and Eastern Europe remains overwhelmingly European—with approximately 85 percent owned by EU investors—declining capital flows from core economies like Germany directly impact regional stability. German foreign direct investment into the region fell by 22.5 percent between 2022 and 2024 without seeing a subsequent recovery.

Export Dependencies Across the Wider Region
The reliance on German and Austrian markets extends well beyond Central Europe’s core industrial base. Data from 2024 indicates that Germany remained the top export destination for Romania at 20.5 percent and for Bulgaria at 15.2 percent. In Poland and Hungary, despite ongoing political debates over economic dominance, Germany accounted for 27.1 percent and 24.9 percent of respective exports in 2024, maintaining a wide margin over any alternative destination.
Meanwhile, Austria anchors banking, services, and industrial input supply chains across Slovenia, Croatia, and the broader Balkan region, frequently serving as the primary foreign investor. This three-decade integration model has kept Central and Eastern Europe more industrialized than the European Union average, but it leaves local economies tethered to external demand fluctuations.

Regional Divergence and Economic Runways
Early symptoms of the broader slowdown are already visible in parts of the region. Industrial output in Hungary and Slovakia contracted throughout 2025, signaling the friction of declining external orders. Conversely, Romania faces distinct fiscal challenges, recording a budget deficit of 9.3 percent of gross domestic product in 2024, the highest within the European Union.
Certain economies have managed to offset shrinking foreign demand through resilient domestic consumption. Poland demonstrated relative insulation, sustaining economic growth supported by strong internal consumer activity.
Related reading
- Central Asian states tighten borders through administrative barriers
- James Mansell Lancaster Jr. Drives SUV Into Kroger Store
- China Eastern flight attendant kneels after cart brushes passenger (archyde.com)
- Belgium’s Defence Minister Warns of ‘Dark Winter for Europe’ as Hybrid Warfare from Russia Threatens Military Readiness (archyworldys.com)