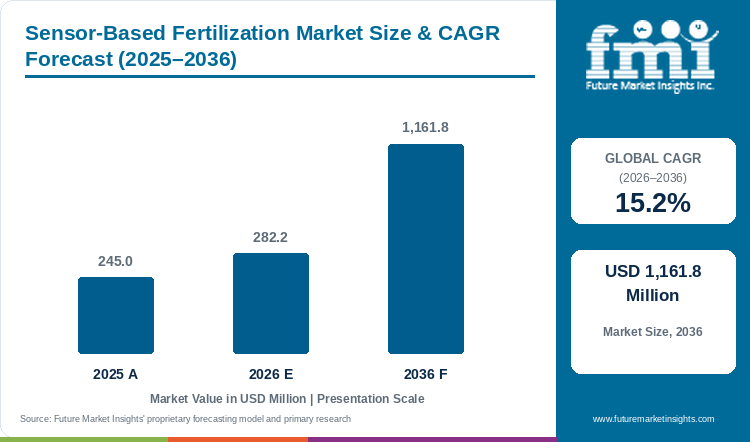
The global sensor-based fertilization market is valued at USD 282.2 million in 2026, advancing from USD 245.0 million in 2025, according to industry valuations. Driven by the direct integration of real-time field data into spreaders, planters, drones, and fertigation systems, the sector is projected to reach USD 1,161.8 million by 2036 at a compound annual growth rate (CAGR) of 15.2%. Adoption is accelerating as agricultural producers seek precision input management, supported by targeted government funding initiatives across international markets.
Market Valuation and Growth Trajectory Through 2036
Growth in the sensor-based fertilization sector relies on precision agriculture tools that measure nutrient requirements on the fly. Hardware and application systems represent the largest offering segment, holding an estimated 48.7% share of the market in 2026. These systems combine crop sensors that evaluate nitrogen status with variable-rate controllers that adjust application volumes as machinery moves across fields. Rather than replacing entire machinery fleets, growers frequently retrofit older fertilizer spreaders with compatible controllers.
Government funding and agricultural modernization programs are lowering adoption barriers. In England, the Farming Equipment and Technology Fund (FETF) specifications issued in March 2026 include crop sensors that measure nitrogen requirements and variable-rate controllers fitted to older spreaders, with a 2025 equipment fund offering a 40% grant for eligible nitrogen sensors and controllers added to older spreaders. Internationally, Japan approved plans in April 2025 to connect sensor data directly with agricultural spraying drones, while South Korea’s smart-farming initiative targets 20% technology coverage across its main field-crop areas.
Technology Segmentation and Drone Adoption
Drone and UAV-based systems capture an estimated 47.2% share of the technology segment in 2026, outperforming stationary ground sensor networks. Drones offer operational flexibility, allowing a single unit to service scattered fields and multiple farm locations while doubling as crop scouting tools prior to fertilizer application. International equipment rollouts illustrate this expansion; DJI Agriculture reported that its Agras T50 and T25 spraying and spreading drones had covered more than 980 million acres across over 100 countries and regions by April 2024.
Despite adoption rates, operators must contend with flight regulations and payload capacity limits that restrict the acreage completed per flight. Ground sensor networks and satellite-imagery-driven platforms capture the remaining market share, serving growers who require continuous in-soil monitoring or large-scale vegetative index mapping.
Crop Types and Regional Implementation Dynamics
Cereals and grains account for 38.8% of crop type demand in 2026, dominating input optimization due to multi-pass application schedules during the growing season. Because cereal crops receive fertilizer multiple times before harvest, they provide frequent windows for variable-rate adjustments based on sensor readings and prescription maps. Historical adoption data supports this baseline; the United States Department of Agriculture's Economic Research Service (USDA ERS) reported variable-rate technology usage on 37.4% of planted U.S. corn acres in 2016 and 18.8% of winter-wheat acres in 2017.
Additional crop categories driving demand include fruits and vegetables, oilseeds and pulses, and turf and ornamentals. Market segmentation by farm size divides adoption across large operations exceeding 1,000 hectares, medium holdings ranging from 100 to 1,000 hectares, and smaller farming enterprises where high equipment and servicing costs remain a primary adoption barrier.
Financial Hurdles and Operational Integration Challenges
High initial equipment costs continue to challenge smaller farming operations throughout the forecast period. Industry analysts emphasize that farm-level adoption depends heavily on machinery compatibility. According to principal analysis from Future Market Insights, farmers routinely assess whether a new prescription system integrates with existing machinery before purchasing; if spreaders cannot execute the generated prescription maps, adoption stalls. Input suppliers must also demonstrate that reductions in chemical fertilizer volume can fully offset upfront setup and ongoing service costs.
Worth a look