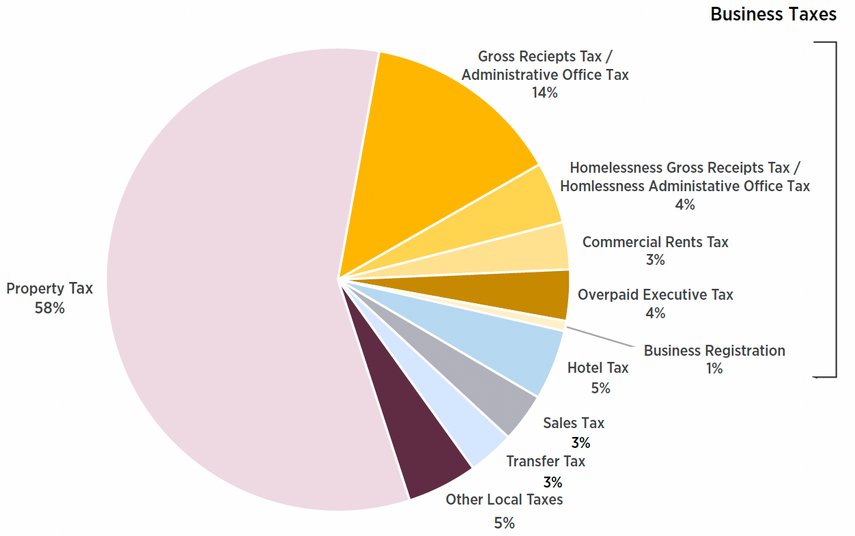
San Francisco real estate investors avoided paying more than $450 million in transfer taxes between 2023 and 2025 by exploiting a distressed debt loophole. Proposition J, a ballot measure placed before voters by a 10–1 vote of the Board of Supervisors, aims to eliminate that exemption for commercial properties, mixed-use buildings, and multi-family residential properties with more than five units effective March 1, 2027.
San Francisco Transfer Tax Loophole Shift
San Francisco traditionally collects a real estate transfer tax scaled by sale price, ranging from 0.50% for properties under $250,000 up to 6% for transactions of $25 million and above, following rate increases approved by voters in 2020. Historically, the city exempted foreclosed properties and properties transferred to lenders in-lieu of foreclosure from this tax to encourage economic activity and make distressed assets more affordable for new buyers.
However, investment patterns shifted dramatically after 2023. Between 2008 and 2023, 4,000 foreclosure exemption claims were filed, with 80% involving single-family homes and 65% following conventional foreclosure patterns where lenders eventually sold the property to a new buyer. Since 2023, investors increasingly acquired distressed debt directly from lenders and foreclosed themselves, bypassing conventional transfers. Data shows that out of 600 recent claims, only 23% involved single-family homes, 56% involved properties valued over $10 million, and fewer than 10% followed the conventional pattern.
Proposition J Tax Exemption Changes
If approved by a simple majority of voters, Proposition J will alter how distressed properties are taxed. Single-family homes and condominium buildings containing up to four units will keep their transfer tax exemptions during foreclosure. Multi-family residential buildings with more than five units, mixed-use buildings, and commercial properties will lose the exemption.
The measure is estimated to generate between $100 million and $150 million annually over its first five years. That revenue projection remains volatile because high foreclosure rates are anticipated in the near term, but revenue could drop significantly once the real estate market stabilizes. The measure also temporarily raises San Francisco’s Gann Limit—a state-imposed cap on municipal spending—by the exact amount of transfer tax collected for four years starting November 3, 2026.

Proposition J and I Affect Transfer Tax Revenue
Proposition J originally accompanied a broader municipal strategy to halve transfer tax rates for transactions exceeding $10 million, reversing the 2020 voter-approved increases. Although the Board of Supervisors withdrew that specific reduction legislation, the mayor pledged to revisit cutting transfer tax rates for high-value properties if Proposition J offsets the resulting financial impact.
At the same time, Proposition I presents a separate policy intersection. Prop I proposes dedicating half of all transfer tax revenue from transactions over $10 million to a specialized fund for affordable housing and homelessness programs, while requiring future voter approval for any transfer tax rate reductions. If both Proposition J and Proposition I pass, generated revenue will partly feed the affordable housing fund, complicating any subsequent reductions in high-value transfer tax rates.
Voter Decision Timeline
San Francisco voters will decide the fate of Proposition J, following its placement by the Board of Supervisors. If passed, the elimination of the commercial and large multi-family foreclosure tax exemption takes effect on March 1, 2027.