Credit Card Delinquency Rates Remain Low Despite Rising Balances
Despite concerns about consumer finances, credit card delinquency rates remained surprisingly low at the end of 2025, even as overall credit card balances continued to climb. This suggests a resilient consumer base supported by strong income growth and healthy balance sheets.
Credit Card Delinquency Rates Decline
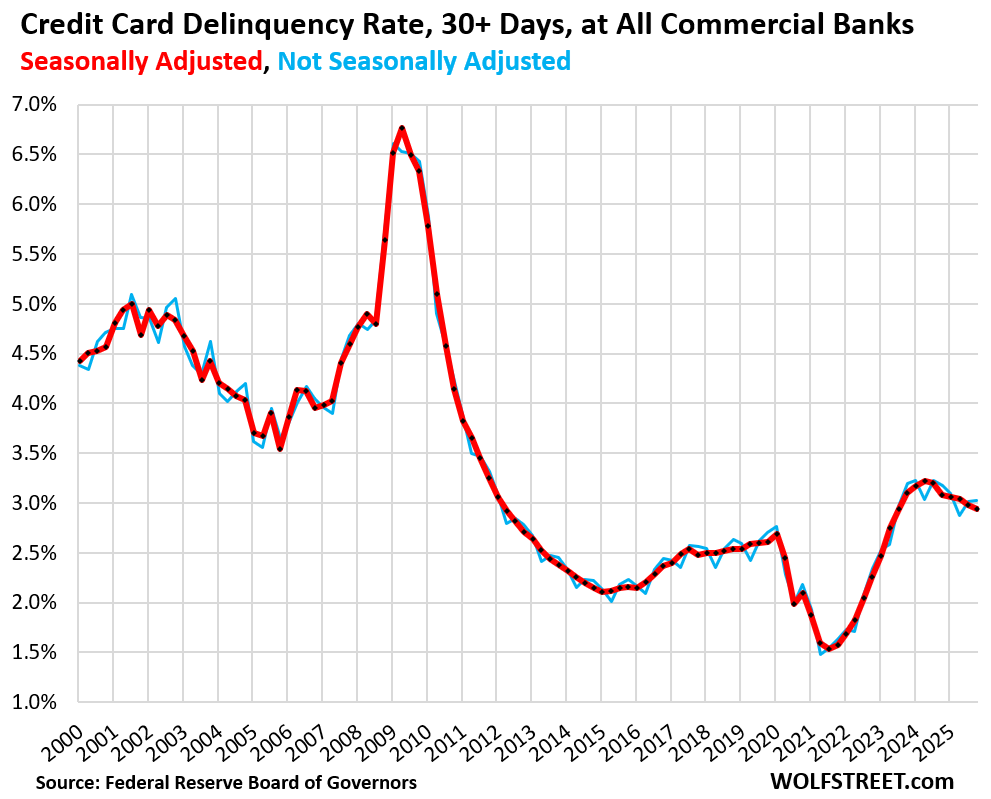
The 30-day-plus delinquency rate on credit cards issued by all commercial banks declined to 2.94% in the fourth quarter of 2025, seasonally adjusted, matching the rate from the third quarter of 2023. This is down from 3.08% a year prior and 3.10% two years ago, according to data released by the Federal Reserve [1]. The non-seasonally adjusted rate also saw a decrease, falling to 3.03%, the lowest for any fourth quarter since 2022.
Delinquency rates had previously dipped during the period of low interest rates but rose slightly after that period ended. However, rates have begun to decline again in 2024, remaining relatively low compared to historical data.
Credit Card Balances Increase
Total credit card balances rose by $69 billion year-over-year in the fourth quarter, a 5.7% increase, reaching $1.28 trillion. This growth is attributed to increased consumer spending and rising prices, as reported by the New York Fed’s Household Debt and Credit report based on Equifax data [1].
Other consumer loans, including personal loans and Buy-Now-Pay-Later (BNPL) loans, saw a more modest increase of 1.1% year-over-year, reaching $560 billion. These loans generally accrue interest, unlike many credit card charges that are paid off monthly.
Strong Consumer Finances Support Spending
The combination of low delinquency rates and rising balances can be explained by several factors. Consumers are earning record incomes, and the number of consumers is at a record high. They are also increasingly utilizing electronic payment methods, with credit cards dominating consumer transactions [1].
a significant portion of households have strong balance sheets, with 65% owning their homes and approximately 40% of homeowners having no mortgage. Over 60% of households also hold stocks, and many have accumulated substantial cash reserves [1].
Debt-to-Income Ratio Remains Manageable
The ratio of credit card and other consumer loan balances to disposable income was 8.0% in the fourth quarter, consistent with the previous year and below pre-pandemic levels. Disposable income, as defined by the Bureau of Economic Analysis, represents after-tax income available for spending, debt servicing, and saving [1].
Available Credit Reaches Record High
Banks are actively encouraging credit card usage by offering rewards programs and increasing credit limits. The aggregate credit limit rose to a record $5.4 trillion, exceeding balances, resulting in a record $4.15 trillion in available unused credit [1].
Third-Party Collections at Record Low
The percentage of consumers with accounts in third-party collections hit a record low of 4.6% in the fourth quarter, indicating fewer defaults and successful debt resolution [1].
Looking Ahead
The current trends suggest continued consumer resilience, supported by strong income growth and healthy balance sheets. However, ongoing monitoring of delinquency rates and credit card balances will be crucial to assess the long-term impact of economic conditions on consumer finances.
Keep reading