Livret A Inheritance Tax Rules in France
When an account holder dies in France, balances held in a tax-free Livret A savings account remain fully subject to inheritance tax obligations, according to banking data published by Selectra. While the state exempts the annual interest earnings on these popular regulated savings accounts from income tax and social levies, the underlying cash deposited by the deceased is treated as standard estate property under French tax law.
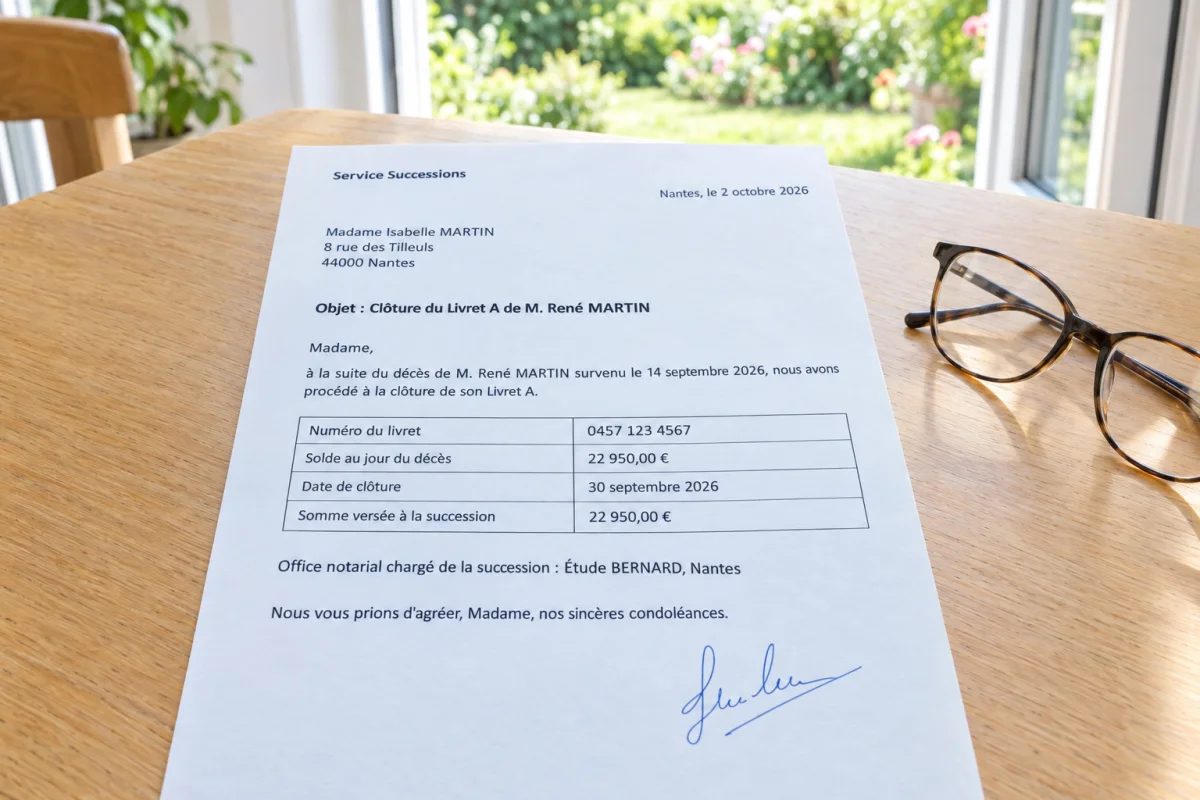
Financial institutions freeze and close a Livret A immediately upon receiving official notification of a customer’s death. The remaining balance—capped at a standard principal of 22,950 euros for individuals, excluding capitalized interest—then flows directly into the broader estate pool to be distributed among legal heirs or designated legatees, as reported by Selectra.
How Inheritance Tax Calculates Across Beneficiary Categories
Inheritance tax liability on a Livret A account depends entirely on the total net assets received by each beneficiary and their familial relationship to the deceased. Tax authorities aggregate all assets from the estate, including real estate holdings and other bank accounts, before subtracting statutory tax-free allowances known as abattements.
Surviving spouses and civil union partners (PACS) receive a total exemption from inheritance taxes in France. Married couples operating under a standard joint property regime share ownership of funds deposited from household income, meaning half of a Livret A balance legally belongs to the surviving spouse automatically, while only the remaining half enters the estate succession.
For other beneficiaries inheriting a maximum-balance Livret A containing 22,950 euros as their sole asset, tax liabilities vary sharply based on kinship:
* Children: Pay 0 euros in tax provided their total received share, including gifts made over the previous 15 years, remains under the 100,000-euro statutory allowance.
* Brothers and sisters: Deduct a 15,932-euro allowance from the balance, leaving the remaining 7,018 euros taxed at a 35% rate, generating a bill of 2,456.30 euros.
* Nieces and nephews as legatees: Deduct a 7,967-euro allowance, leaving 14,983 euros taxed at 55%, resulting in 8,240.65 euros owed.
* Friends or cohabiting partners (concubins) named in a will: Deduct a 1,594-euro allowance, leaving 21,356 euros taxed at 60%, totaling 12,813.60 euros.
Brothers and sisters can avoid these succession charges entirely if they meet three strict criteria simultaneously at the time of the death: they must be single, widowed, divorced, or separated; they must be over 50 years old or suffer from a disability preventing work; and they must have lived continuously with the deceased during the five years preceding the death.
Managing Bank Closures and Estate Declarations
Beyond inheritance taxes levied by the state, families dealing with a deceased relative’s accounts face administrative charges from financial institutions. Banks can bill administrative fees for processing succession paperwork up to a regulated limit of 857 euros, which remains entirely separate from state inheritance duties.
Heirs must declare the Livret A balance alongside all other estate assets during official succession filings. Missing statutory deadlines for these declarations triggers late-payment interest penalties enforced by tax authorities. For individuals planning their own estate distribution, financial advisors note that while a Livret A offers high liquidity during life, alternative vehicles like life insurance policies follow distinct regulatory frameworks for transmission outside of close family structures.
Frequently Asked Questions About Livret A Successions
Does the 22,950-euro Livret A ceiling apply to the amount entered into the succession?
No. While 22,950 euros is the standard deposit cap for individual account holders, annual interest earnings capitalize over time and remain inside the account. The exact sum entering the estate succession is the total ledger balance recorded on the actual day of death.
Are cohabiting partners entitled to inherit a Livret A without a will?
No. Unmarried partners have no legal status or automatic inheritance rights under French succession law. A cohabiting partner or friend can only receive funds from a Livret A if the account holder explicitly designated them as a beneficiary in a formal written testament.
How are bank succession fees regulated when closing the account?
Banks charge administrative fees to process estate closures, but these costs are legally capped at a maximum of 857 euros. These operational fees are entirely distinct from the inheritance taxes calculated and collected by tax authorities.
Worth a look