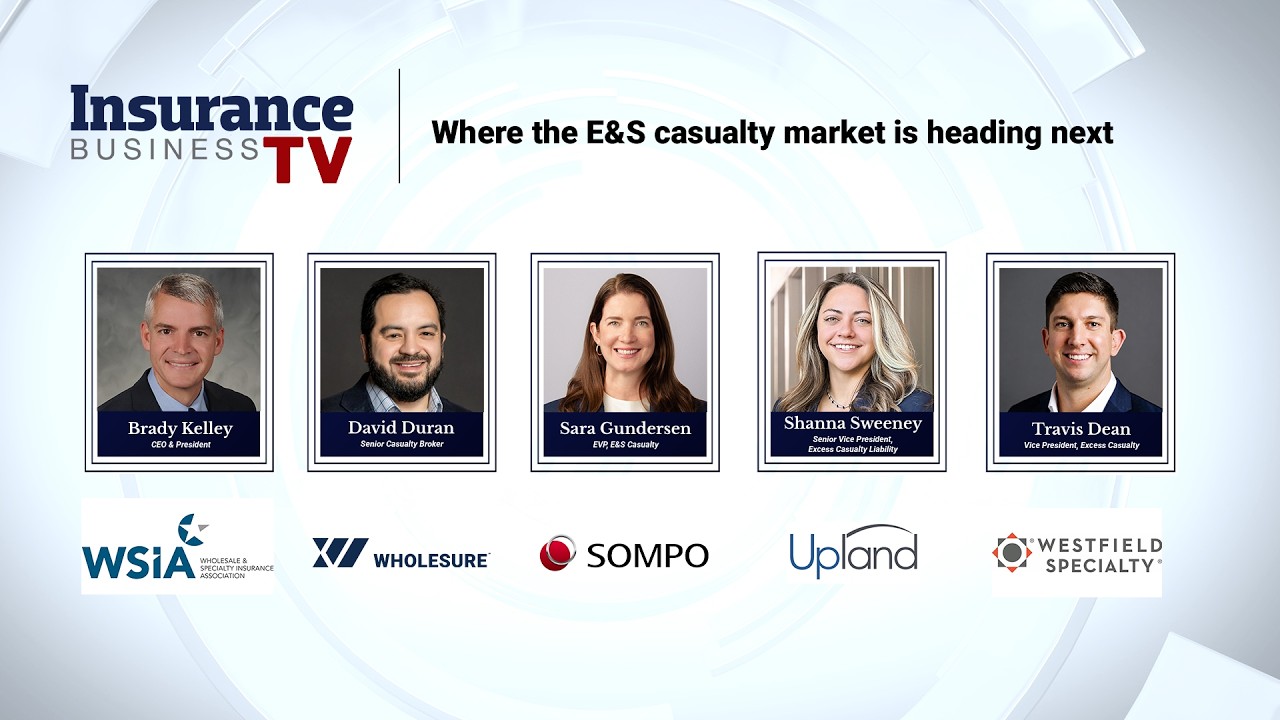
Surplus lines premium reached $129.8 billion in 2024, according to data from WSIA cited by CEO and President Brady Kelley. Industry leaders analyzing the current landscape in 2026 report that while overall volume continues to expand, localized pockets of softening and rising severity drivers are reshaping how carriers underwrite complex risks.
Surplus Lines Premium Reaches $129.8 Billion Amid 2025 Growth Projections
The excess and surplus (E&S) market demonstrated sustained expansion following its 2024 performance. Reporting data from 15 states with surplus line stamping offices showed growth of roughly 8% through 2025, according to WSIA statistics provided by Brady Kelley. When AM Best publishes its official 2025 report, nationwide premium is anticipated to land between $140 billion and $141 billion. Nonprofessional liability coverage grew by just under 12% in 2025 to represent about 38% of stamping office premium, while professional liability lines such as D&O and E&O saw a 5.1% increase.
Sompo and Westfield Specialty Track Increased Market Competition
Market dynamics are shifting away from the strict hard market conditions observed between 2020 and 2024. Sara Gundersen, Executive Vice President of E&S Casualty at Sompo, noted that submissions to the firm continue to climb year over year by roughly 20%, though the marketplace halfway through 2026 contains notable pockets of softening and heightened competition. Travis Dean, Vice President of Excess Casualty at Westfield Specialty, explained that retail carriers and international markets from Bermuda and London have grown more aggressive, bringing supply and demand closer to equilibrium.
Construction Defect Claims and Office Conversions Create New Risk Exposures
Underwriters face emerging hazards tied to contemporary structural projects and shifting urban real estate. Shanna Sweeney, Senior Vice President of Excess Casualty Liability at Upland Specialty Insurance, pointed out that risks featuring a combination of severity drivers—such as unfavorable jurisdictions paired with auto exposure or residential construction action-over claims—remain difficult to place. Meanwhile, Travis Dean highlighted data center and office conversion projects as unique sources of exposure. Data centers carry pollution and intensive resource consumption risks where a minor roof leak can trigger severe equipment failure and subsequent construction defect claims. Similarly, large-scale conversions of vacant office spaces into apartments, condos, and hotels introduce complex exposures stemming from gut demolition, added elevator banks, and extensive plumbing work.
Wholesale Brokers and Carriers Prioritize Expertise and Underwriting Discipline
Securing complex casualty business requires a distinct blend of analytical rigor and market responsiveness. Sara Gundersen emphasized that winning carriers must balance underwriting discipline with the freedom of rate and form. David Duran, Senior Casualty Broker at Wholesure, stated that success hinges on three core pillars: expertise, relationships, and execution. According to Duran, complex accounts are won by clearly articulating the story behind the risk to ensure underwriters receive complete exposure details.
Frequently Asked Questions
What caused the hard insurance market between 2020 and 2024?
Travis Dean of Westfield Specialty explained that retail carriers became highly conservative regarding both capacity and appetite during those years, creating a supply deficit that E&S and new specialty market entrants subsequently filled.
Which specific E&S sectors represent the strongest growth areas?
Shanna Sweeney of Upland Specialty Insurance identified infrastructure, civil contractors, specialty trades, well-controlled construction projects, product liability, and agricultural operations—including agritainment and equipment distribution—as key growth segments.
How much did professional liability lines grow in 2025?
Data from the 15 states with surplus line stamping offices showed a 5.1% growth rate for professional liability lines like D&O, E&O, and medical malpractice in 2025, according to WSIA figures shared by Brady Kelley.
Keep reading