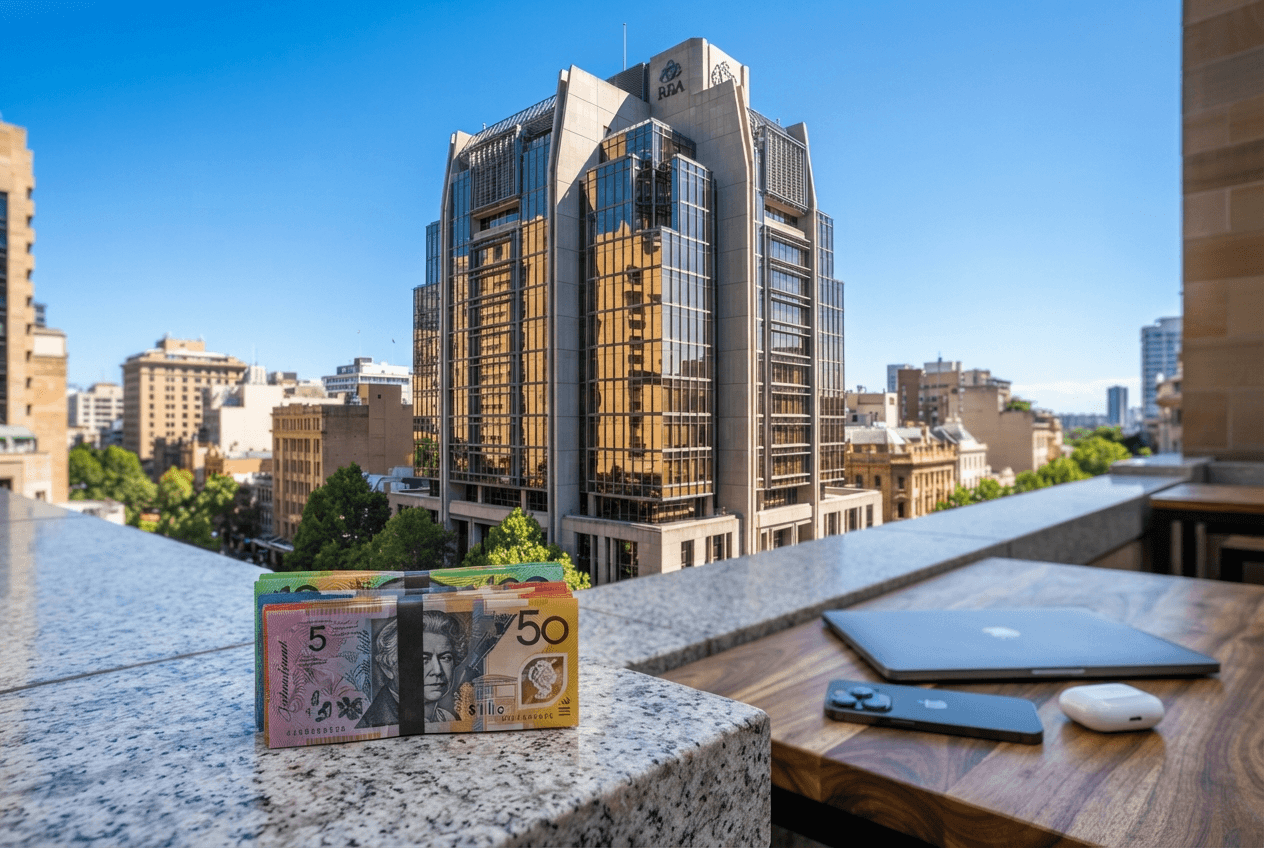
The Reserve Bank of Australia raised its official cash rate by 25 basis points to 4.6 percent, marking the highest level in 15 years and representing the fourth rate hike of 2026. According to the central bank’s policy statement, the move aims to counter sticky inflation that is failing to return toward the target band of 2 to 3 percent.
Australia’s Interest Rate Hike and Economic Slowdown
The central bank’s decision brings cumulative rate increases to 100 basis points for the year. Officials pointed to escalating global energy prices driven by the expanding conflict in the Middle East and unexpected technology-related price pressures from artificial intelligence demand as primary inflation drivers. Bank of America analysts noted that July consumer price data signaled accelerating inflation rather than a return to target, alongside secondary pressures from energy costs.
Despite tighter monetary policy, Australia’s gross domestic product growth slowed to 2.1 percent in the second quarter, down from 2.5 percent in the previous quarter. Financial markets showed a muted reaction to the announcement, with both the S&P/ASX 200 and the Australian dollar showing little movement. The Reserve Bank of Australia signaled that further increases remain possible.
Global Economic Divergence and Bond Yields
The global economy exhibits a split environment. The Organisation for Economic Co-operation and Development revised its global GDP growth forecast slightly upward to 2.9 percent, supported by record industrial production and export levels. Global equities have reached record highs, propelled by strong earnings momentum in the technology sector and AI infrastructure development, even as bond yields climb to multi-decade highs.
However, growth remains uneven. Europe and the United Kingdom face a two-speed economic environment where domestic service sectors expand while export-oriented manufacturing struggles against weak foreign demand and supply chain costs. Concurrently, rising global bond yields reflect structural pressures, including the unwinding of yen carry trades as the Bank of Japan faces pressure to raise its benchmark rate from 1.25 percent to 2.00 percent.
Energy Markets and Central Bank Outlook
Energy price volatility continues to shape monetary policy trajectories worldwide. Although crude oil prices recently fell below $100 per barrel, analysts attribute the decline to temporary buffers such as strategic reserve releases, lower Chinese energy imports, and a global pivot to coal rather than a permanent resolution of supply constraints. The Reserve Bank of Australia warned that unresolved geopolitical conflicts could sustain higher inflation and lower economic activity than currently projected, framing an exacting final quarter for global financial markets in 2026.
Related reading