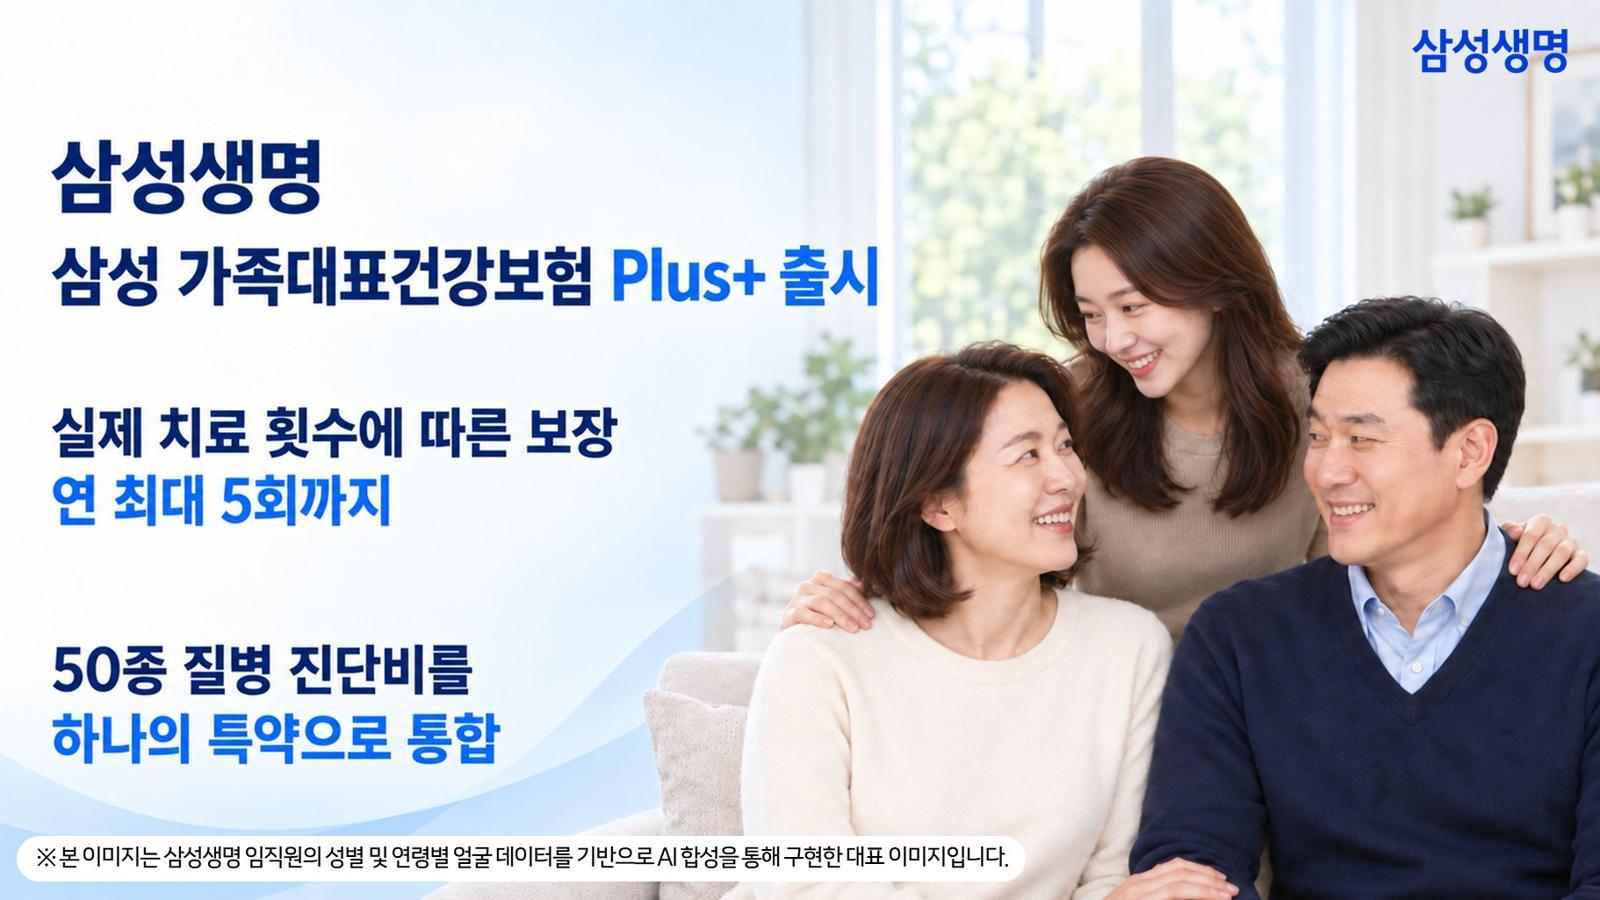
Titled the “Samsung Family Representative Health Insurance Plus+” (non-participating, no-refund type), the product is designed to strengthen core coverages from existing series to increase practical utility during actual medical treatments.
Three Core Pillars of Coverage Enhancement
According to Samsung Life Insurance, the new insurance plan focuses on three core directions to reduce coverage gaps and improve customer convenience: payouts based on treatment frequency, integration of diagnostic ranges, and comprehensive coverage across the entire treatment journey.
Under the revised terms, the “Cancer Integrated Coverage (maximum 5 complex treatments per year at general hospitals or higher) and Accidental Death Coverage Special Provision” distributes payouts based on the actual number of treatments received. While older complex treatment riders required patients to undergo at least two treatments before triggering a payout, the updated policy issues payouts starting from the very first treatment.
Payout Structure and Financial Limits
The policy utilizes a cumulative payout structure for treatments received. Based on a special provision subscription amount of 1억 원, the plan provides 2000만 원 for each treatment session from the first up to the fifth, delivering an annual maximum of 1억 원 in treatment costs, as reported by Samsung Life Insurance.
Additionally, the policy includes a separate accidental death benefit. In the event of a fatal accidental injury, the plan pays out 100% of the special provision subscription amount as an additional accidental death insurance claim.
Simplified Claims and Diagnostic Integration
To reduce administrative hurdles, Samsung Life Insurance has consolidated several previously fragmented disease diagnosis fees into single riders. The new offerings include the “Power Diagnosis (Types 1-8 Diseases) Special Provision,” “Power Diagnosis II (Types 1-5 Diseases) Special Provision,” “50s Disease Diagnosis Special Provision,” and “18s Disease Diagnosis Special Provision.”
According to the company, these integrated riders allow policyholders to claim insurance money using only disease codes (KCD) without requiring separate paperwork. By merging coverage types that previously required multiple subscriptions into a single rider, the product also lowers overall premium burdens for customers.