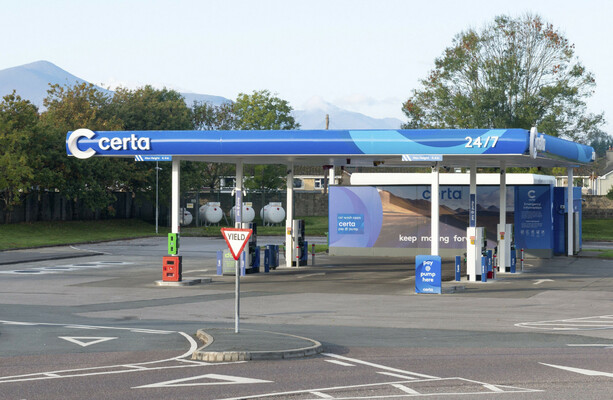
A group of private equity firms has agreed to acquire Dublin-based DCC in a transaction valued at nearly €7 billion, concluding a months-long pursuit and marking the end of the line for Ireland’s last corporate conglomerate. While the deal commands a massive price tag for one of the largest companies produced in Ireland, the transaction drew little public attention outside financial circles, reflecting the low profile of a business best known to Irish consumers through subsidiaries like Flogas and Certa.
DCC Sale Ends Era of the Irish Conglomerate as Private Equity Steps In
The sale underscores a broader structural shift away from diversified business models. Founded in 1976 as a venture capital firm, DCC operated across three primary sectors: healthcare, technology, and energy. In recent years, however, the company systematically divested non-core assets to focus entirely on energy. Last year, DCC sold its entire healthcare division, followed by the offloading of its technology operations in 2026. Those two transactions brought in approximately £1.15 billion, or about €1.3 billion, leaving the energy division as the primary driver behind the nearly €7 billion acquisition.
The Rise and Fall of Irish Conglomerates
Conglomerates were once a semi-regular feature of Irish business, though never extremely common. Alongside DCC, several high-profile multi-industry groups have come and gone over the decades:
- James Crean: Originating from a soap distribution business, the company expanded into print and packaging, frozen meals, and engineering and welding, eventually becoming one of the top 10 companies on the Irish stock exchange by value.
- IWP International: Established in the 1930s, the firm grew rapidly in the 1980s across cosmetics, toiletries, cleaning products, and household goods.
- Fitzwilton plc: Functioned as an investment vehicle for Tony O’Reilly, considered Ireland’s first billionaire, acquiring stakes in textiles, fertilizer manufacturing, and supermarkets.
- The Quinn Group: Helmed by Seán Quinn, Ireland’s richest man at the height of the Celtic Tiger, the group invested in plastics, cement, and insurance.
Other entities such as Independent News and Media in the media sector and the Irish Agricultural Wholesale Society in agriculture and food pursued distinct multi-sector or specialized growth strategies before eventually being sold off, broken up, going bust or getting consolidated.
Understanding the Conglomerate Discount
The systematic dismantling of these corporate groups stems from long-standing market skepticism toward diversified business models. Investors routinely price conglomerates at less than the sum of their individual operating parts—a phenomenon known in finance as the “conglomerate discount.” For instance, if a parent group houses three distinct units valued at €100 million each, the combined entity may trade at a valuation closer to €200 million.
This discount is attributed to the inherent complexity of analyzing multi-industry firms, which leads to a more cautious investor approach and suppressed valuations. Multiple studies indicate that conglomerates frequently allocate capital less efficiently than standalone enterprises, often funneling excess funds into weaker divisions while starving high-potential units of necessary investment.
Corporate realities frequently catch up to these structural inefficiencies. Research tracking 165 conglomerates found that just 32 percent—or 53 companies—remained diversified businesses 15 years later. For DCC, the transition mirrors this global trend: while energy accounted for roughly half of group operating profits 15 years ago, as of 2026 it is responsible for almost all of the company’s value.
Worth a look