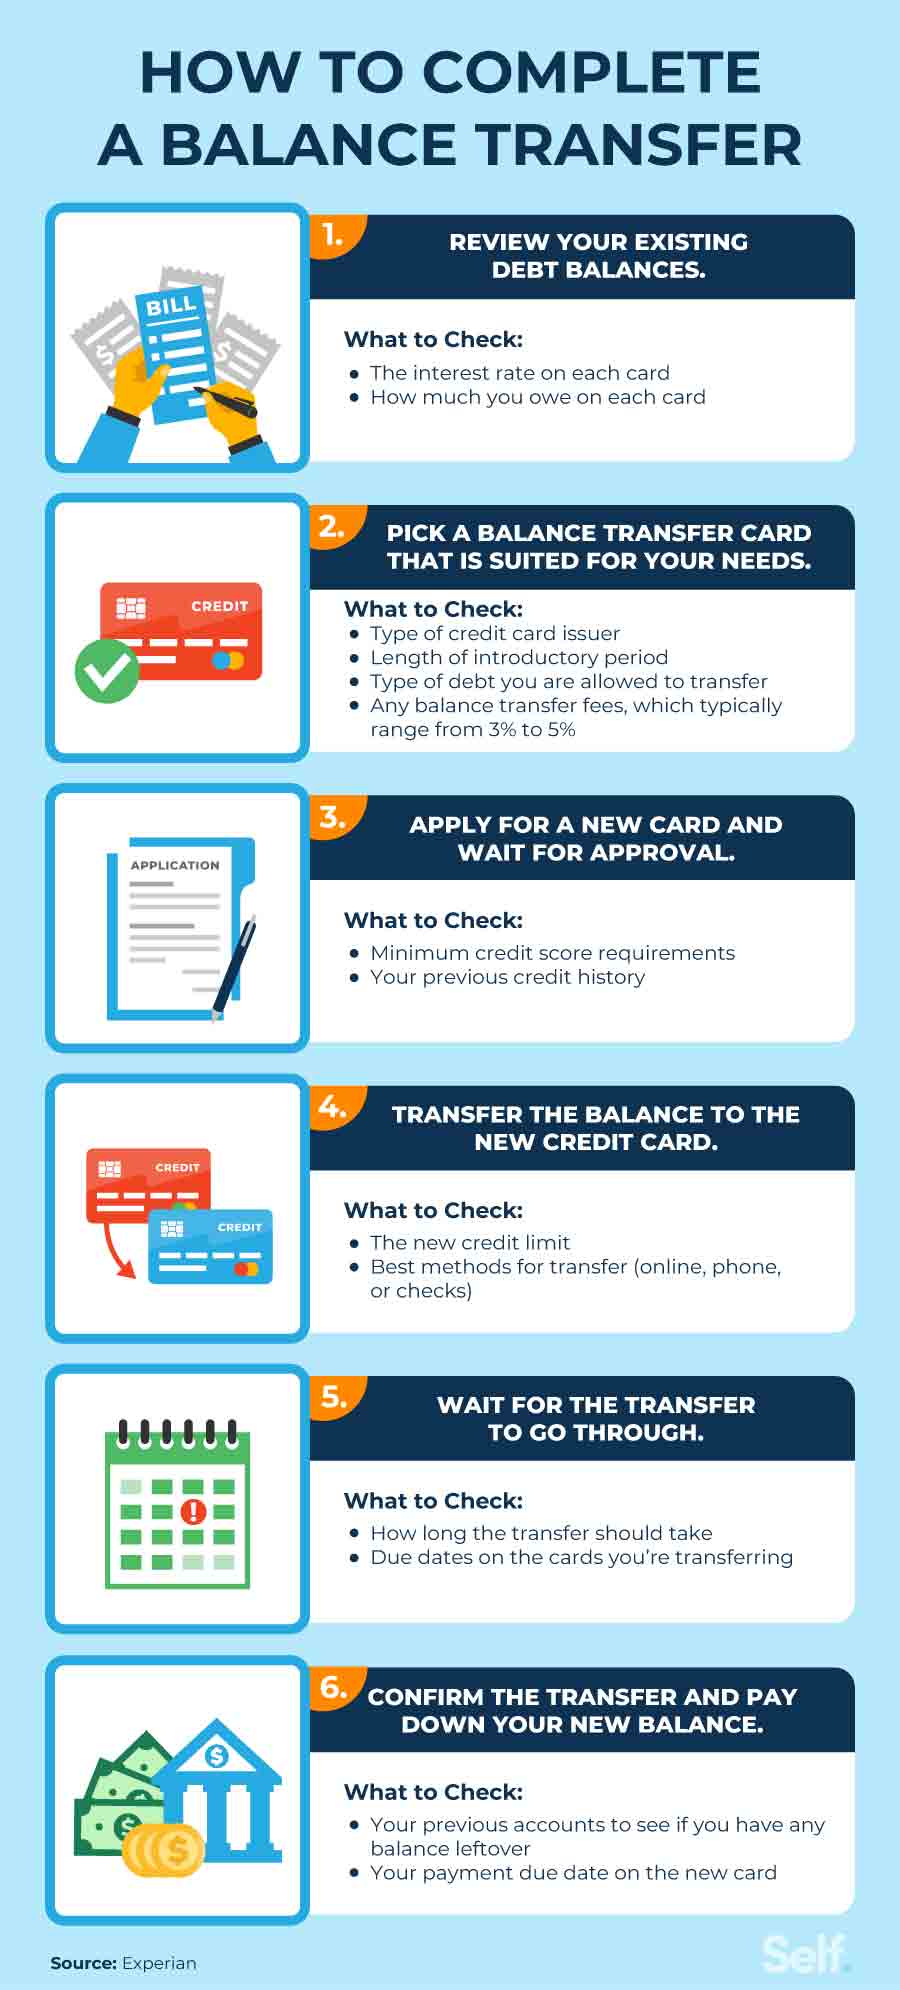
A Bank of America balance transfer allows cardholders to move high-interest debt from existing credit cards or loans to a new Bank of America credit card, typically to utilize a 0% introductory APR offer. This strategy consolidates debt into a single payment, though it requires careful management of transfer fees and strict adherence to repayment timelines to avoid interest charges.
Calculating the Cost of Interest Savings
A balance transfer functions as a tool to reduce interest costs by shifting debt to a card with a lower rate. Bank, the primary advantage is the ability to direct more of each monthly payment toward the principal balance rather than interest. For example, transferring a $5,000 balance from a card with a 15% APR to one with a 0% promotional APR eliminates interest charges for the duration of the offer, provided the debt is cleared before the promotional window closes.
Before initiating a transfer, borrowers must account for transaction fees. Bank of America typically charges a fee ranging from 3% to 5% of the total amount transferred. A consumer must calculate whether the total interest saved over the promotional period outweighs these upfront costs.
Comparing BankAmericard and Customized Cash Rewards
Bank of America offers specific credit products designed for debt consolidation, each with distinct terms regarding introductory periods and fees. The BankAmericard® Credit Card serves as the institution’s primary balance transfer option, offering a 0% introductory APR for 21 billing cycles on transfers made within the first 60 days of account opening. This card does not feature a rewards program, functioning strictly as a debt-payoff instrument, and carries a 5% balance transfer fee.
Alternatively, the Bank of America® Customized Cash Rewards Credit Card provides a 0% introductory APR for 15 billing cycles on balance transfers executed within the first 60 days. The fee structure for this card starts at 3% for transfers made during the initial 60-day window, after which it increases to 5%.
The Transfer Timeline
To initiate a transfer, an account holder must provide the account number of the originating debt and the specific amount to be moved.
Borrowers should maintain payments on their old accounts until the transfer is officially confirmed to avoid late fees. Once the transfer is active, the focus must shift to a disciplined repayment plan. Because the 0% APR is a temporary window, missing a payment can result in the loss of the promotional rate, causing standard interest to accrue on the remaining balance.
Avoiding the Debt Accumulation Trap
A balance transfer is most effective when the cardholder stops using the old, now-paid-off credit cards. If a borrower continues to accumulate new debt on the original cards while paying off the transferred balance, they risk increasing their total debt load rather than reducing it. Effective debt management requires a commitment to not adding new charges to the accounts that have been cleared through the transfer process.
Keep reading