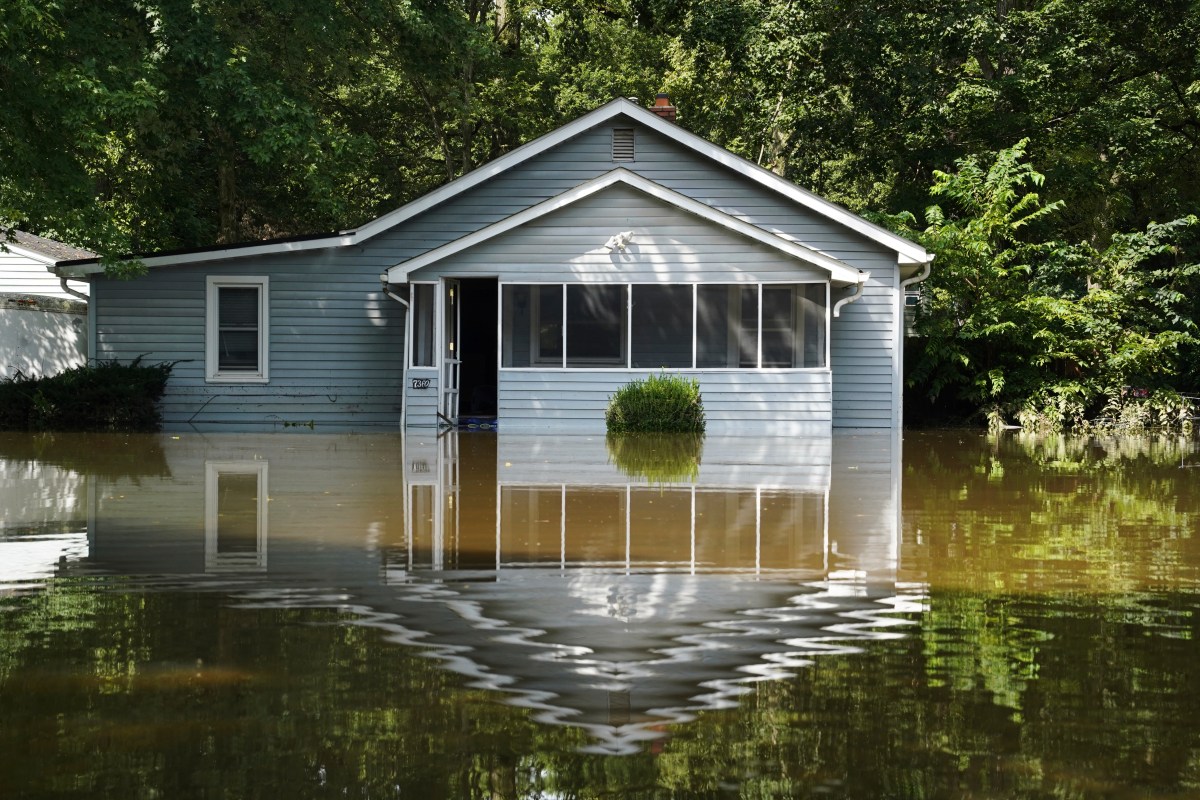
A “Godzilla” El Niño pattern could reshape U.S. winter weather, increasing perils for some homeowners and lowering risks for others, according to the National Oceanic and Atmospheric Administration (NOAA) and reporting by Newsweek.
What is a Godzilla El Niño and how will it impact U.S. weather patterns?
Meteorologists at NOAA predict that a naturally recurring climate pattern of warmer Pacific waters will become “very strong” this fall and winter. Scott Handel, lead meteorologist at NOAA’s Climate Prediction Center, told Newsweek that no two El Niños are exactly the same, but distinct regional risks are expected.
The West Coast, particularly California, has a higher chance of heavy precipitation and flooding. The Southeast is more prone to heavy rain, flooding, and severe weather. Meanwhile, the Upper Midwest and Northern Tier will likely see above-average temperatures, while the Northern Rockies and northern Cascades tend to experience a reduced snowpack.
Why are millions of homeowners facing high flood risks without insurance?
El Niño has traditionally lowered the risk of devastating Atlantic hurricanes, offering historic relief to homeowners on the Southeast coast, especially in a vulnerable state like Florida. However, the heightened threat of heavy rainfall and flooding undermines those benefits, exposing a major insurance gap across the country.
A recent U.S. Government Accountability Office report reveals that 86 percent of properties at high risk of flooding lack flood insurance. Dr. Howard Botts, chief scientist at real estate analytics platform Cotality, told Newsweek that standard homeowners policies rarely cover flood damage, leaving the financial burden on the NFIP and unprotected property owners.

Cotality’s 2026 Hurricane Risk Report shows that rainfall flooding accounts for about 37 percent of expected annual loss among homes at high risk of hurricane-driven flooding outside mandatory flood insurance areas. Furthermore, FEMA maps often fail to capture the true scope of vulnerability. According to Denali Pinto, a research data analyst at the Scripps Institution of Oceanography at the University of California, San Diego, who spoke with Newsweek, approximately thirty percent of payouts issued by the National Flood Insurance Program over the past ten years originated outside of currently designated high-risk flood zones.
What steps should property owners take before the winter storm season peaks?
Experts urge at-risk residents to secure flood insurance through the National Flood Insurance Program or a private carrier. Scripps climate economist Tom Corringham explained to Newsweek that because NFIP protection generally entails a 30-day waiting period, attempting to purchase a policy as soon as a major storm emerges on the weather map is usually too late.
Homeowners can purchase up to $250,000 in building coverage and $100,000 in contents coverage through the NFIP. Renters are also eligible to buy contents coverage of up to $100,000, though policies do not cover temporary housing or additional living expenses.
How will El Niño affect insurance premiums and policy pricing?
This year’s “super” El Niño would not change NFIP policy prices, according to Corringham. He told Newsweek that seasonal El Niño conditions are not a household-level rating variable under FEMA’s Risk Rating 2.0 system.
Private insurers operate with greater flexibility and utilize sophisticated catastrophe models. Yet, Corringham pointed out that he would not anticipate an immediate, steep spike in deductibles or premiums for Southern California homeowners simply because NOAA forecasts an El Niño winter. Insurers typically smooth forward-looking weather risks over at least five years to avoid large year-to-year changes in premiums.
Frequently Asked Questions
Where can residents check their specific flood zone status?
Property owners can search online for “what is my flood zone” and enter their address at FEMA’s Map Service Center to determine their risk, according to Scripps research data analyst Denali Pinto.

Do standard homeowners insurance policies cover mudslides and earth movement?
Scripps researchers point out that while difference-in-conditions policies commonly insure against land movement and landslides—issues frequently triggered by saturated soils during severe rainstorms—such coverage may face limitations in regions highly prone to landslides, such as California.
Worth a look