Home equity represents the financial difference between a property’s market value and the remaining balance on its mortgage. According to Hills Bank, homeowners build this asset through regular mortgage payments, creating a secure form of collateral that can back loans or lines of credit for major expenses.
How Do Home Equity Loans Differ From HELOCs?
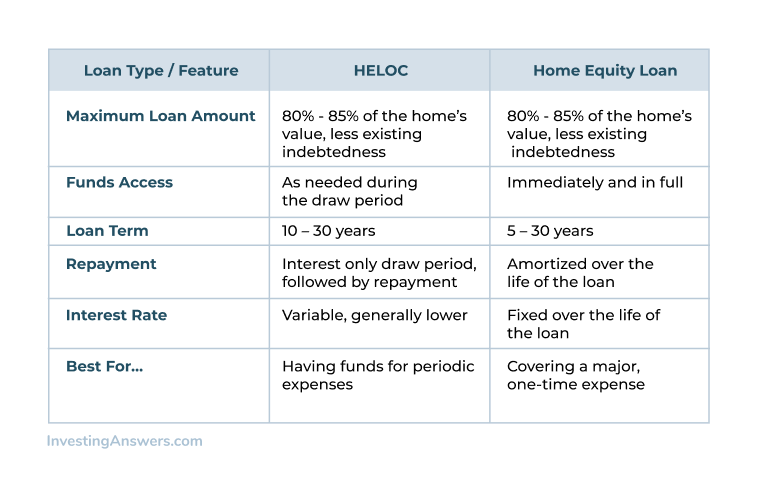
A home equity loan delivers a single lump sum of money upfront, featuring fixed monthly payments and a set maturity date that mirrors a traditional auto loan. In contrast, a home equity line of credit (HELOC) operates much like a credit card, allowing borrowers to draw funds flexibly up to an approved limit as expenses arise.
HELOC borrowers only pay interest on the active balance and can repay and redraw funds repeatedly without reapplying. Conversely, securing additional funds through a home equity loan requires submitting a new application since the original financing is fully disbursed at closing.
What Are Common Uses for These Financing Options?
Home equity loans suit single-expense purchases requiring one lump sum, frequently covering debt consolidation, large home repairs, or extensive renovations. HELOCs accommodate ongoing or staggered expenses, making them practical for long-term home remodeling projects or recurring repair costs where bills arrive in stages.
Frequently Asked Questions
Can borrowers use a home equity loan for non-housing expenses?
Yes, funds from a home equity loan can finance nearly any major purchase or financial obligation, though borrowers frequently choose them for debt consolidation and home improvements.
Do HELOC borrowers have to reapply every time they need money?
No, borrowers can draw against an open HELOC repeatedly up to their approved limit without reapplying, unless they want to increase their maximum borrowing capacity.

How are monthly payments structured for a home equity loan?
Home equity loans feature equal, predictable monthly payments calculated from the original loan amount and repayment term.
Worth a look