India Reaches 8.7 GWh of Installed BESS Capacity as Solar and Wind Integration Accelerates
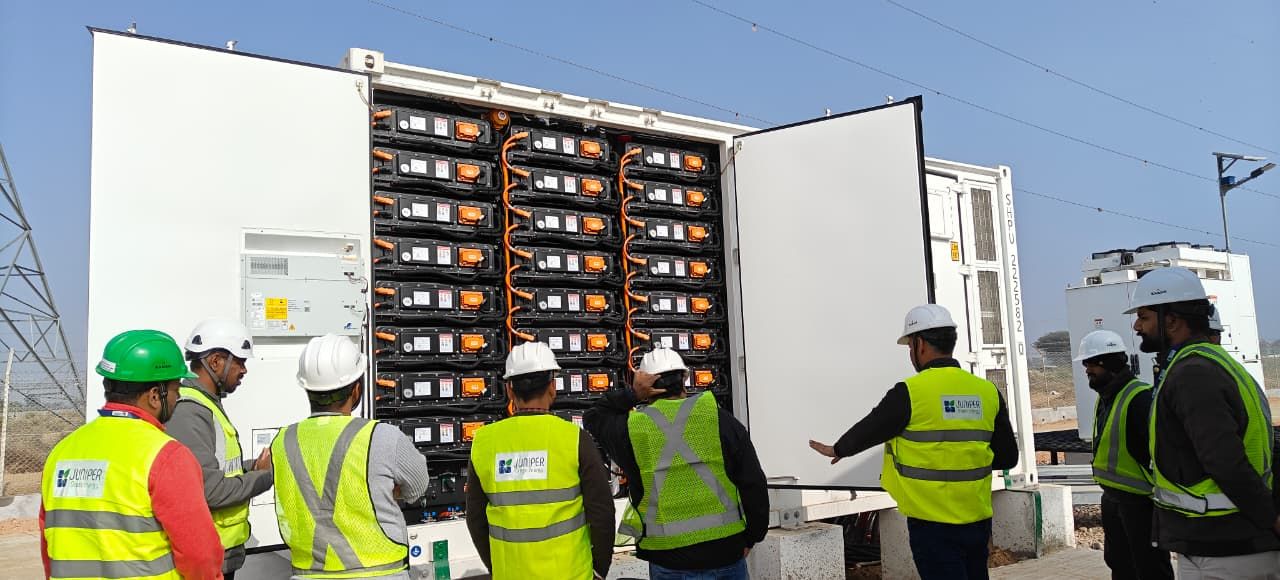
India’s renewable energy sector has reached 288.58 GW of total installed capacity as of June 2026, driven by 162.15 GW of solar and 57.44 GW of wind power, Energetica India reported. Integrating this variable generation into the grid has driven rapid deployment of energy storage systems. According to a report by the India Energy Storage Alliance (IESA) cited by Energetica India, India’s cumulative installed battery energy storage system (BESS) capacity reached 8.7 GWh in the first half of 2026, with 7.1 GWh of that total added during H1 alone. About 53 GWh of BESS projects are currently under execution across the country.
Upstream Manufacturing Capacity Lags Behind Surging Domestic Demand
While downstream deployment accelerates, India’s domestic manufacturing supply chain faces a significant capacity gap. According to data reported by Energy-Storage.news, India’s installed lithium-ion cell manufacturing capacity stands at approximately 2 GWh, creating continued reliance on foreign imports. Announced domestic manufacturing projects are projected to reach 60 to 70 GWh by 2030. The assembly stage shows stronger figures, with cell- and pack-to-container BESS capacity expected to reach between 180 and 220 GWh by 2030. However, these figures represent nameplate projections rather than actual output or full utilization rates, which leaves domestic manufacturers under ongoing cost pressure from international competitors, particularly in China.
Dhruv Garg, Energy Finance Analyst at IEEFA, noted in data reported by Energetica India that overall battery demand is projected to expand at a 36.5 percent compound annual growth rate to reach about 272 GWh by fiscal year 2030. While this growth creates a strong foundation for a domestic manufacturing base, the current reliance on imported cells heightens long-term import dependence.

Policy Interventions and Regional Mandates Shape the Storage Pipeline
To reduce import dependency and stimulate local production, the Government of India has deployed Production Linked Incentive (PLI) schemes, higher Basic Customs Duty on imports, increased Goods and Services Tax (GST) rates, and Minimum Local Content (MLC) requirements. Regulatory enablers are also expanding across federal and state levels. The Central Electricity Authority has proposed mandatory energy storage for all new solar and wind projects starting in 2027, featuring grid-forming capabilities. The Union Cabinet has also approved Phase 3 of the Green Energy Corridor scheme, earmarking INR 50,000 crore (US$5.19 billion) to support 50 GWh of BESS development.
State governments are implementing parallel mandates to drive procurement. Chhattisgarh has proposed mandatory BESS installations for renewable energy projects exceeding 5 MW, while the Kerala State Electricity Regulatory Commission (KSERC) has proposed an 85 percent round-trip efficiency benchmark. Priya Selvaraj, Vice President, Global Business Development – Renewable Power at ABB India, told Energetica India that commercial and industrial (C&I) customers such as data centers, hospitals, and transit networks are prioritizing reliability and power quality, helping establish benchmarks for system performance alongside utility-scale projects.
Tariff Adjustments and Tendering Activity Reflect Market Maturation
Market pricing mechanisms are showing signs of stabilization following years of declining costs. IESA market data reported by Energy-Storage.news indicates that solar-plus-BESS tariffs dropped from INR 6.99 per kWh in 2018 to INR 3.13 per kWh by January 2026, but have plateaued between INR 2.7 and INR 3.5 per kWh since mid-2024. Standalone BESS tariffs bottomed out at INR 1.48 lacs per MW per month in November 2025 before rebounding nearly 59 percent to INR 2.35 lacs per MW per month by September 2026. Rising raw material expenses have pushed re-tendered bids at entities like MSEDCL and SJVN higher by at least one lakh compared to previous discoveries.
Despite these cost adjustments, tendering activity remains high. Approximately 12 GWh of fresh tenders were issued in September 2026 alone. Major utility projects continue to scale up: Adani’s portfolio at Khavda reached 6.63 GWh, making it the largest single-location battery plant in the world, while ACME’s Rajasthan portfolio expanded to 4.95 GWh.
Industry Explores New Chemistries to Support Growth
Industry stakeholders are exploring new revenue streams and alternative technologies to support future growth. Meanwhile, lithium iron phosphate (LFP) maintains a technology roadmap extending to 2035, pointing toward the use of multiple energy storage chemistries across diverse operational use cases.
Worth a look