Household Debt Climbs to $19.1 Trillion
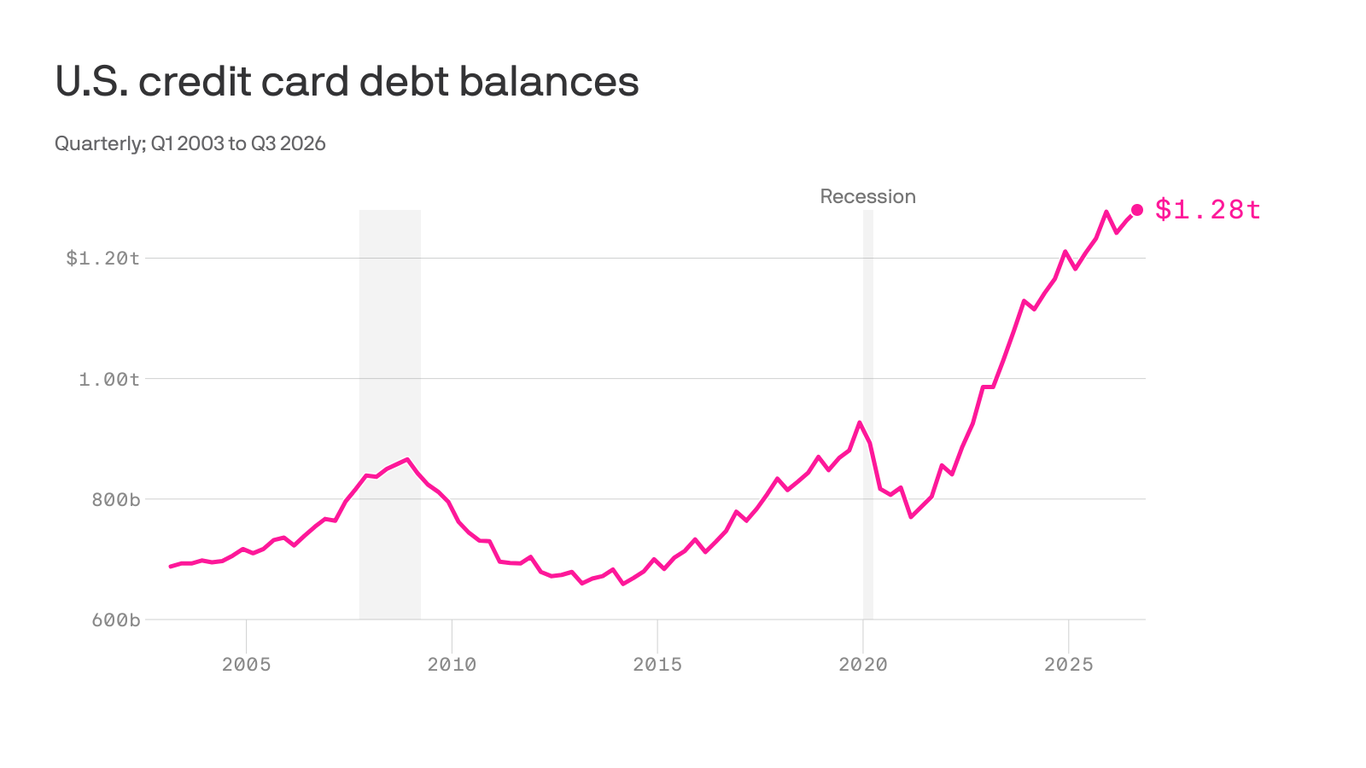
Consumer credit card balances rose by $22 billion in the third quarter, marking a 1.7% increase.
That total stands $52 billion higher than a year earlier. The figures are not adjusted for inflation, meaning higher prices account for a portion of the increase.
Total household debt reached a record $19.1 trillion in the third quarter after a $334 billion increase. That overall sum is up $5 trillion since 2019.
Delinquency Rates Edge Down Overall
Fewer credit card balances are becoming seriously delinquent. That trend signals improvement in how well Americans keep up with payments.
The rate for credit card debt becoming seriously overdue edged down to 6.9% in the third quarter. That percentage remains above the 5.2% rate recorded before the pandemic.
Federal Reserve data shows that consumers younger than 30 experienced the greatest frequency of credit card debt freshly slipping into 90-day delinquency status.
Income Disparities in Credit Delinquencies
Americans in lower-income neighborhoods struggle more with credit card payments than wealthier counterparts do, according to a Federal Reserve report.
Delinquency rates remain above pre-pandemic levels across all neighborhood-income groups. The gap between the richest and poorest areas has widened since 2022.
Over the preceding twelve months, serious credit card delinquencies reached 10.3% among residents living in the least affluent areas. That figure is more than double the 4.4% delinquency rate recorded in the wealthiest neighborhoods.
Average Balances and Economic Pressures
The average credit card balance per borrower sits at $6,678, according to TransUnion’s third-quarter insights report.
How Household Debt and Delinquency Rates Have Grown
How much has household debt grown since 2019?
Total household debt is up $5 trillion since 2019, just before the pandemic began. It reached a record $19.1 trillion in the third quarter.
What is the delinquency rate in lowest-income neighborhoods?
During the past year, serious credit card delinquencies hit 10.3% in areas with the lowest incomes. This rate is more than double the 4.4% recorded in the wealthiest neighborhoods.
Which age group has the highest rate of overdue debt?
Based on figures from the Federal Reserve, consumers under the age of 30 registered the maximum share of credit card obligations newly falling at least 90 days behind.
Worth a look