Global Debt to Hit 100% of GDP as IMF Urges Fiscal Discipline
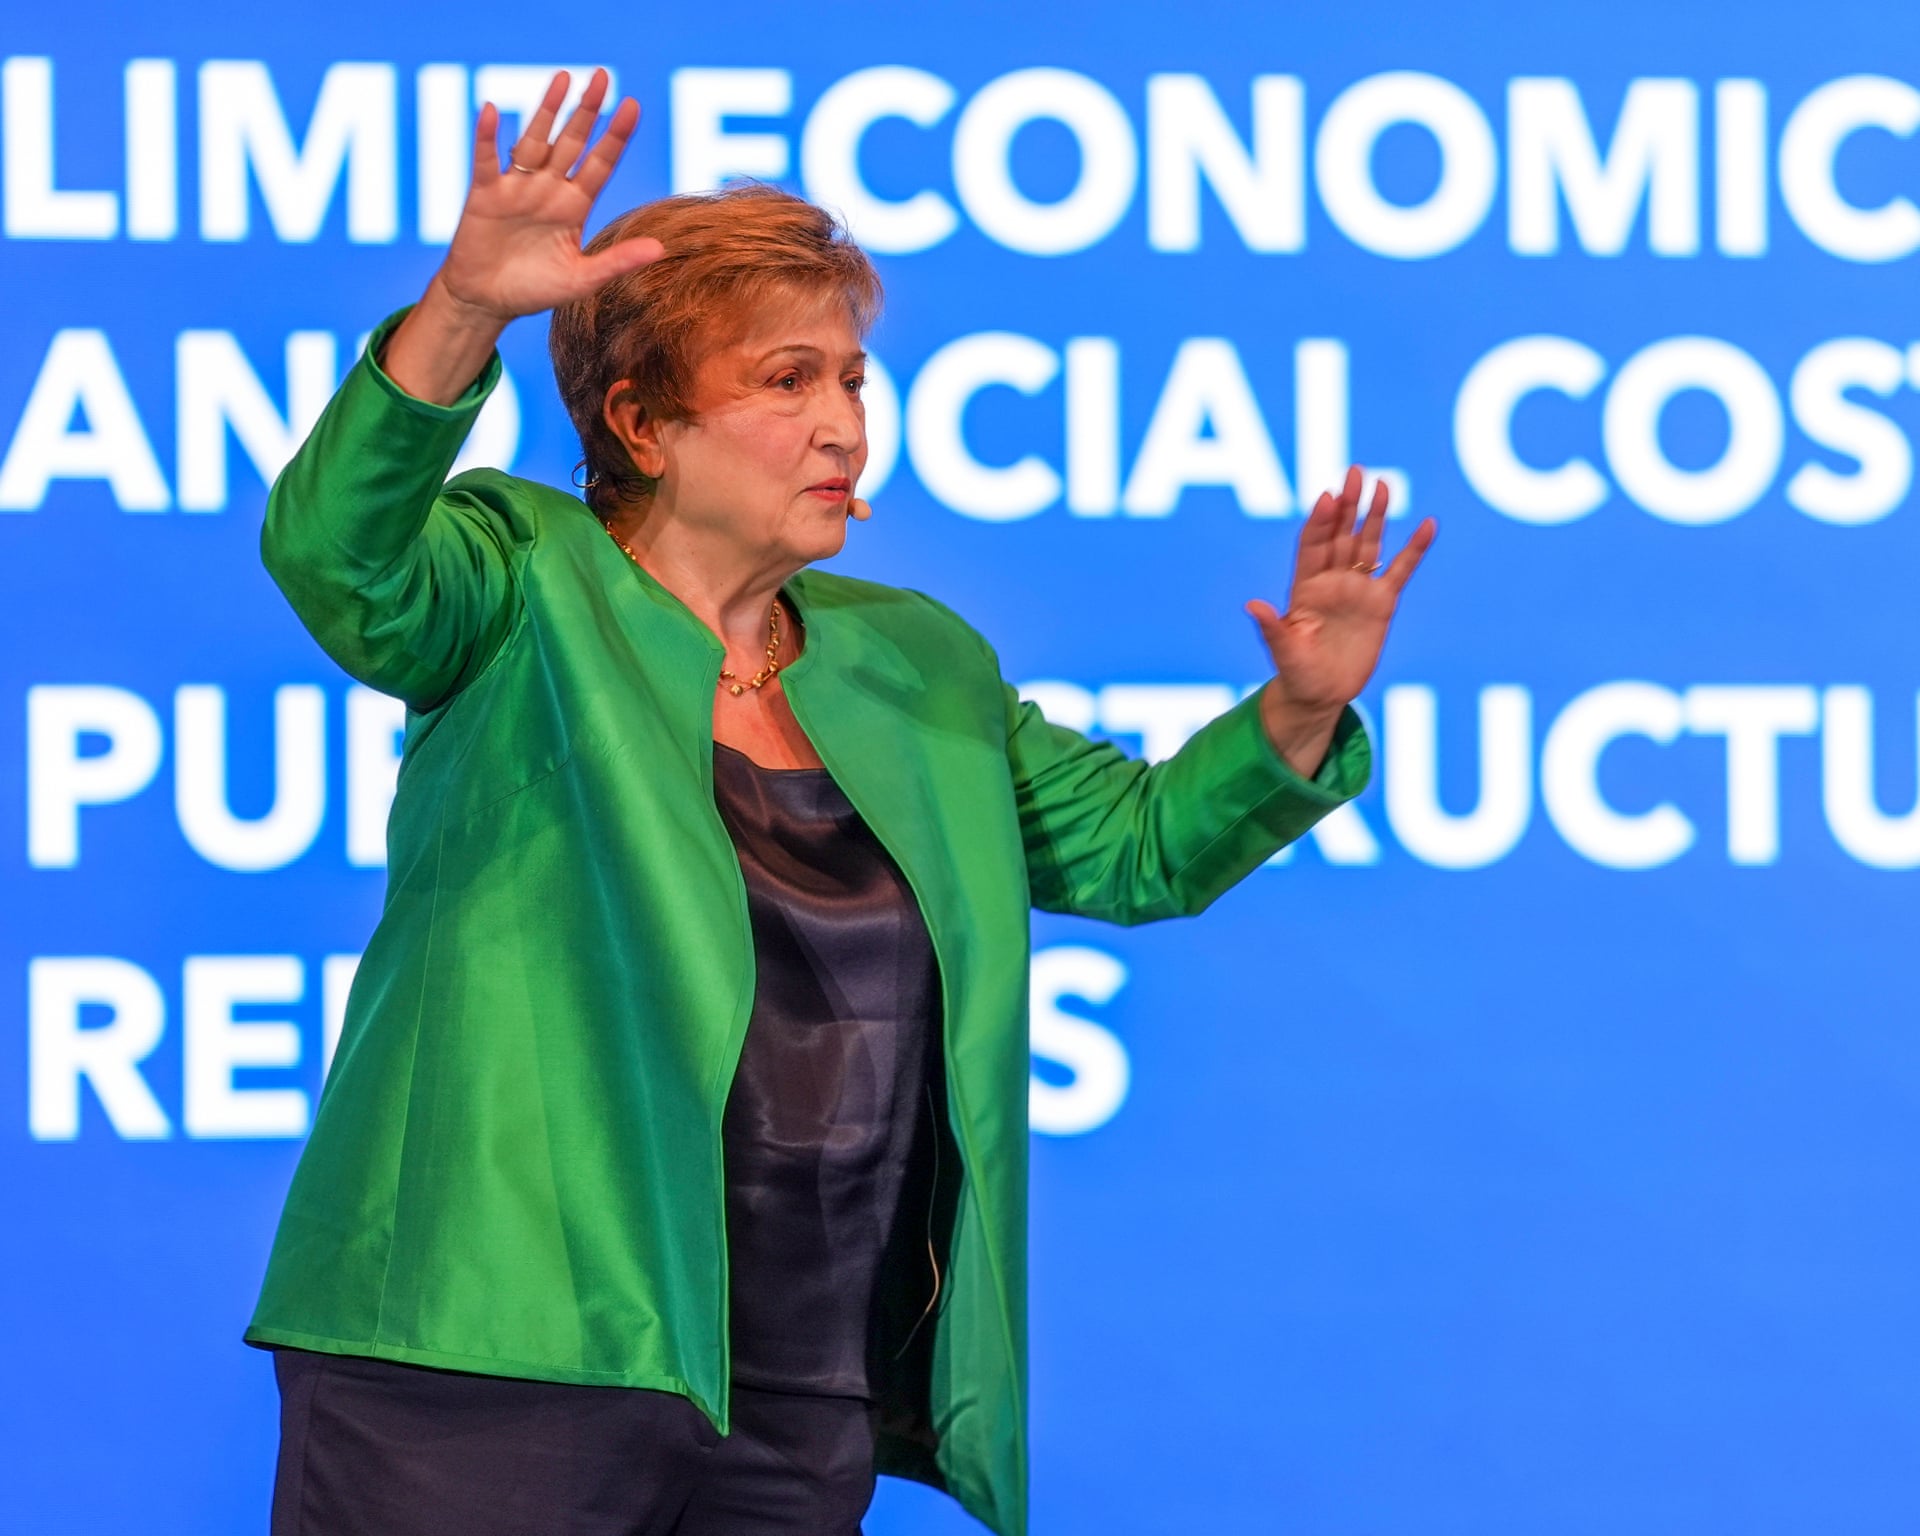
International Monetary Fund Managing Director Kristalina Georgieva called on major economies to tighten fiscal policy as soaring bond yields squeeze national budgets. Speaking in Singapore ahead of the annual meetings in Bangkok, Georgieva warned that global debt-to-GDP ratios have reached their highest level since the Second World War and are on track to hit 100% in coming years.
Bond Yields Push Borrowing Costs to Multi-Decade Highs
Government bond yields have climbed sharply in recent weeks as markets adjust to inflation risks driven by the war in the Middle East. These elevated yields inflate interest bills at a time when budget constraints are tight and defense spending demands are rising. Georgieva stated that high-debt advanced economies need credible medium-term fiscal consolidation plans supported by upfront fiscal measures, noting that countries cannot rely on rapid economic growth alone to outpace their debt burdens.
Central Banks Weigh Monetary Policy Shifts
Central banks should maintain a prudently hawkish bias to combat resurgent inflation, according to the IMF chief. While the European Central Bank, the US Federal Reserve, and the Bank of Japan have already tightened monetary policy, the Bank of England has kept its benchmark interest rate on hold at 3.75%. Georgieva described the rate hikes by the Fed, ECB, and Bank of Japan as highly appropriate given current economic conditions.
Artificial Intelligence Brings Growth and Market Perils
Artificial intelligence adoption could add half a percentage point to global economic growth, but the technology also carries substantial risks. Georgieva urged policymakers to manage potential labor market fallout, serious cyber threats, and frontier models that could run amok. Bank of England Governor Andrew Bailey, who chairs the Financial Stability Forum, recently echoed these concerns, warning of real and significant risks from frontier AI models and calling for the “right to intervene”.
Worth a look