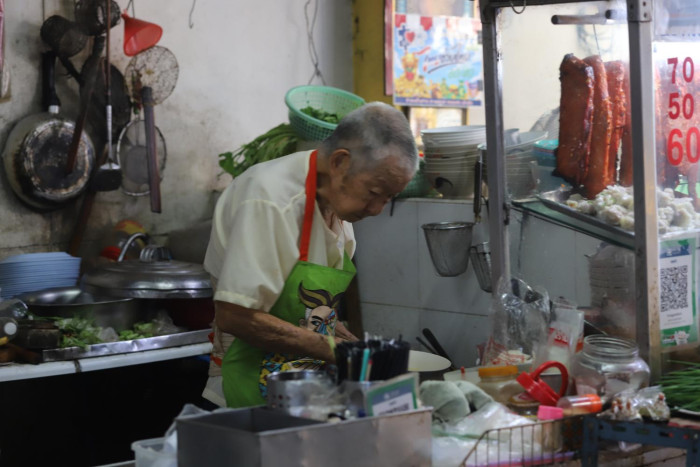
Bangkok Pork Shop Owner Keeps Working at 92 as Thailand Faces Pension Crunch
According to the Bangkok Post, a 92-year-old vendor running a red pork rice establishment near the Bangkok City Pillar Shrine labors on for self-sustenance, highlighting a national trend where almost 70% of older Thais either depend on their offspring for financial aid or labor onward to survive.
Research by Kiatnakin Phatra Financial Group (KKP) indicates that Thailand’s social safety net falls progressively short in catering to its fast-aging populace, given that individuals past age 60 are estimated to comprise 33% of the demographic within the next quarter-century. The bank found that individuals over 60 currently represent 24% of the country’s total population. The country is moving toward becoming a fully aged society while its income per capita remains relatively low, ageing faster than regional peers despite a comparatively low income level.
Government Welfare Limitations Force Workers Into Reliance on Families
Amid strict limitations in government welfare provisions, more than 54% of Thai workers remain outside the social security system entirely. Meanwhile, the government old-age allowance covers only about 7% of elderly living expenses, putting mounting pressure on the Social Security Fund reserves.
These factors show that relying solely on government welfare is insufficient to maintain a reasonable quality of life after retirement,
said Pipat Luengnaruemitchai, chief economist at KKP. Government social welfare benefits could also decline over the next 20 years as the financial burden continues to increase.
Data from the KKP assessment reveals that 86% of the population in Thailand has either failed to create a savings strategy or has been unable to maintain one successfully. Over 80% of existing household savings are concentrated in bank deposits and other low-risk assets that generate returns well below inflation rates.
Rising Medical Costs Compound Financial Pressures for Aging Citizens
Longer life expectancies are adding to the financial strain, with approximately 47% of people who reach age 60 projected to live until at least 85. At the same time, Thailand’s medical cost inflation is forecast to climb to 14.8% in 2026, significantly outpacing headline inflation rates.
As Pipat Luengnaruemitchai pointed out, these challenges are exacerbated by climbing medical expenditures because health coverage plans increasingly implement co-payment structures forcing insured individuals to bear a larger portion of treatment bills. Consequently, investment strategies capable of generating returns above inflation have become essential for retirees.
Two-Stage Retirement Investment Strategy Launches to Combat Deficits
To help cope with these demographic challenges, KKP introduced a two-stage retirement investment strategy designed to help investors accumulate wealth before leaving the workforce and generate regular income afterward, according to Narit Kosalathip, KKP’s head of personal investment advisory.
The first stage features four KKP Ready Retire funds targeting retirement in 2035 and 2045, which include retirement mutual fund (RMF) options. These funds automatically adjust their investment risk levels as investors approach retirement before transitioning into retirement income funds.
The second stage comprises KKP Lifelong Income and KKP Advanced Income. These combine high-quality dividend-paying stocks with fixed-income assets to combat inflation. Retirees benefit from an automated redemption system that delivers consistent cash flow, aiding either the preservation of wealth for future heirs or structured payouts to fund retirement years.
Worth a look